-
-
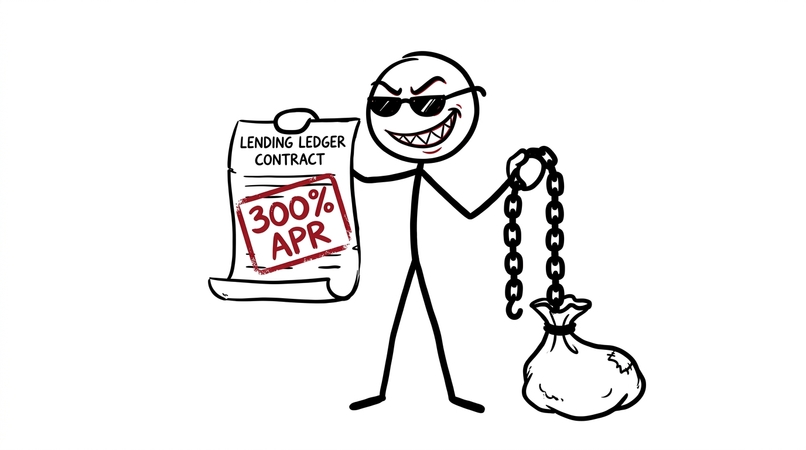
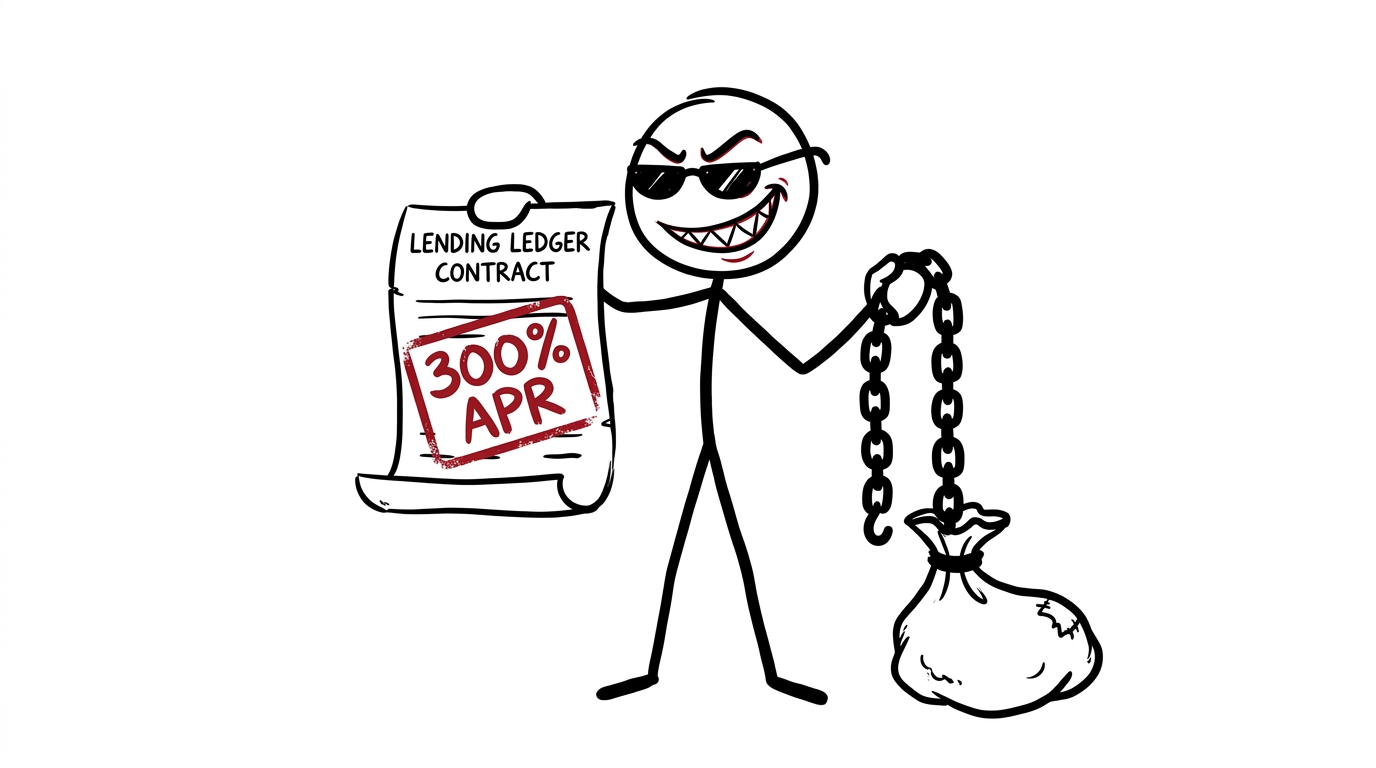
With no formal credit, 40M vendors pay loan sharks >300% APR just to start their day.
-
FinFlow (VyaparSetu) — Algorithmic micro-liquidity & climate resilience on India's DPI stack.
-
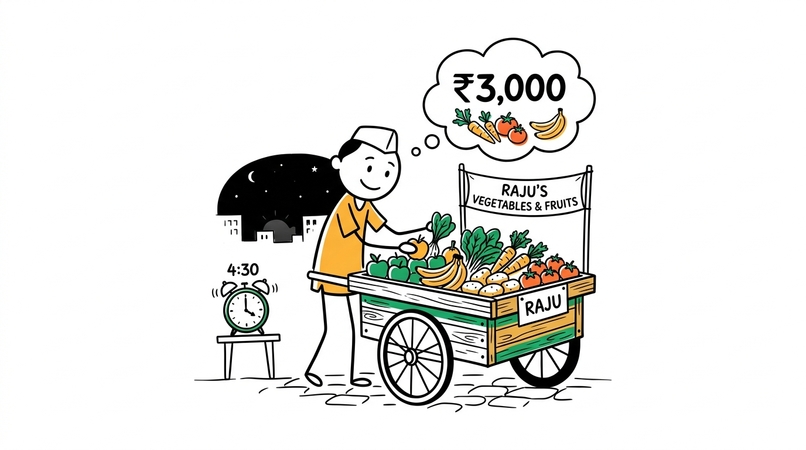
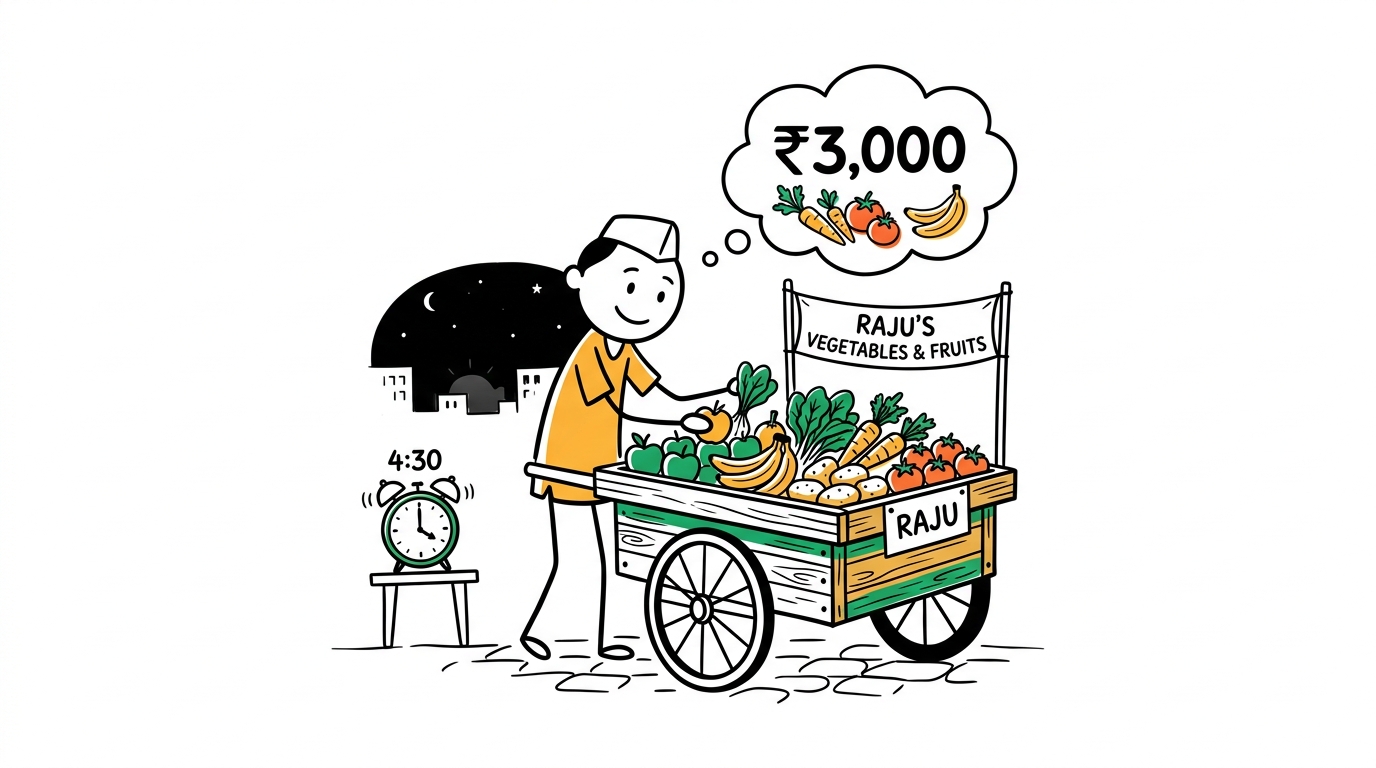
4:30 AM. Raju needs ₹3,000 for wholesale inventory. Banks are closed. The mandi isn't.
-
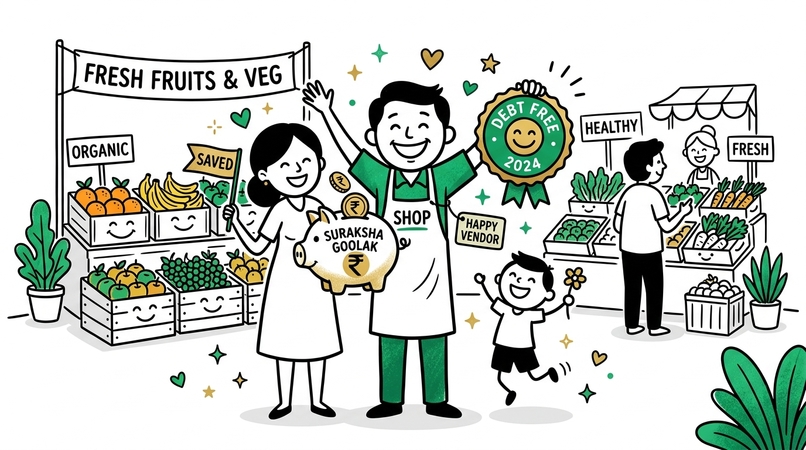
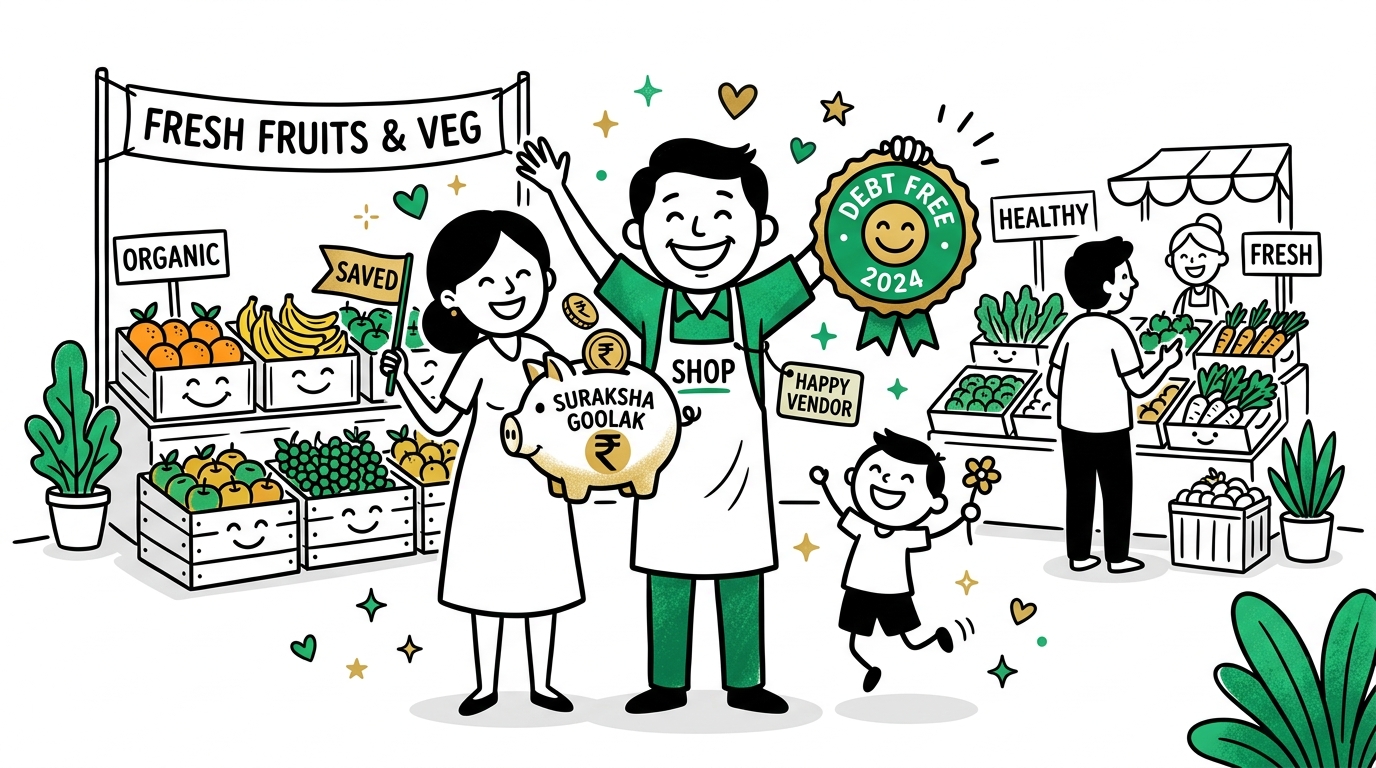
Sunrise Capital at ₹20/day flat fee. Suraksha Goolak savings. Raju is now debt-free.
-
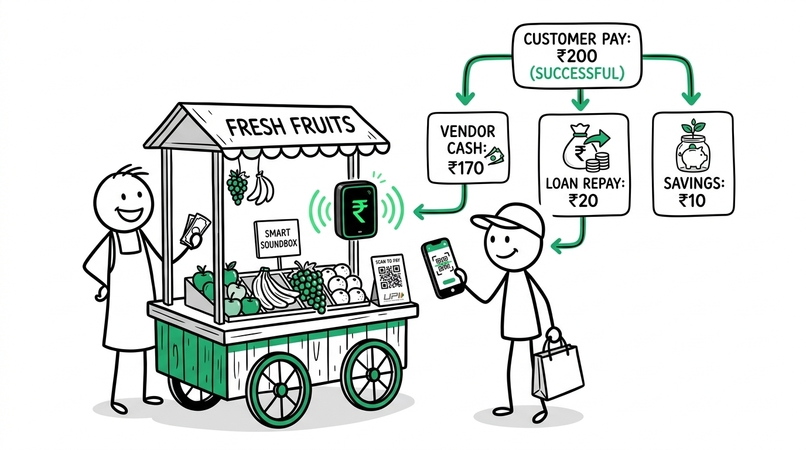
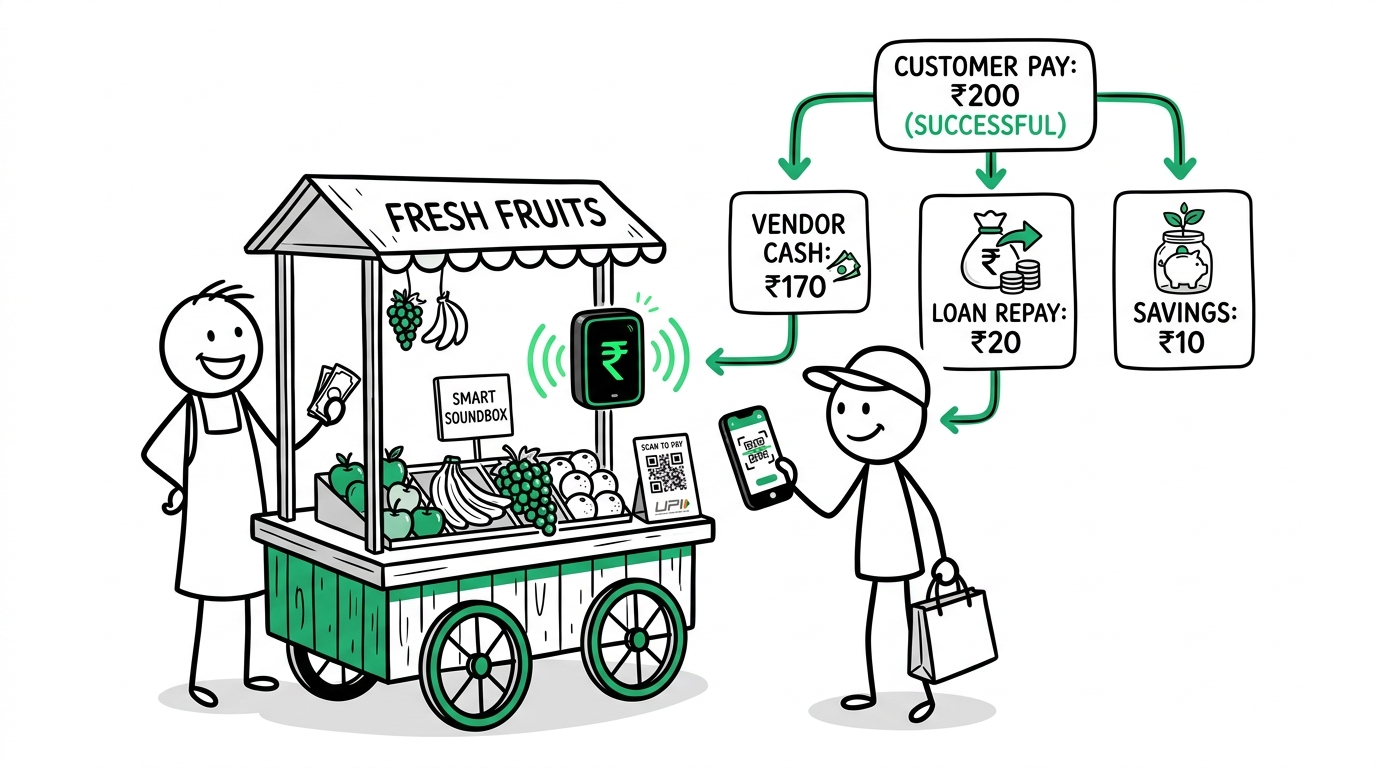
FinFlow auto-repays via Reverse Micro-Skimming — 5–10% deducted from each UPI sale. No EMIs.
-
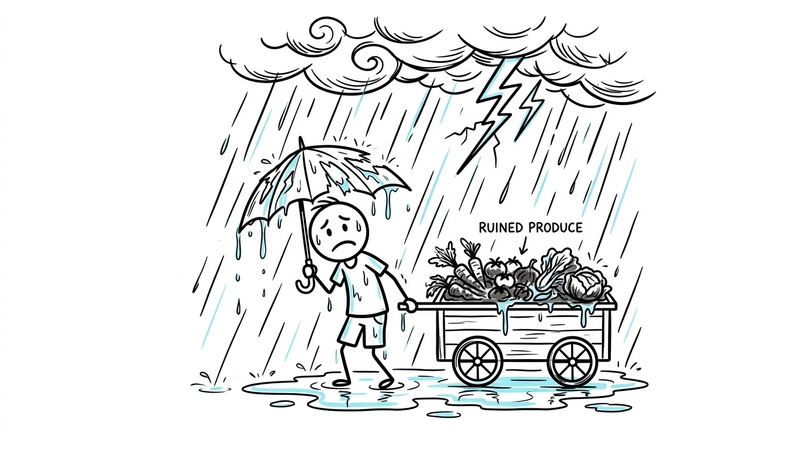
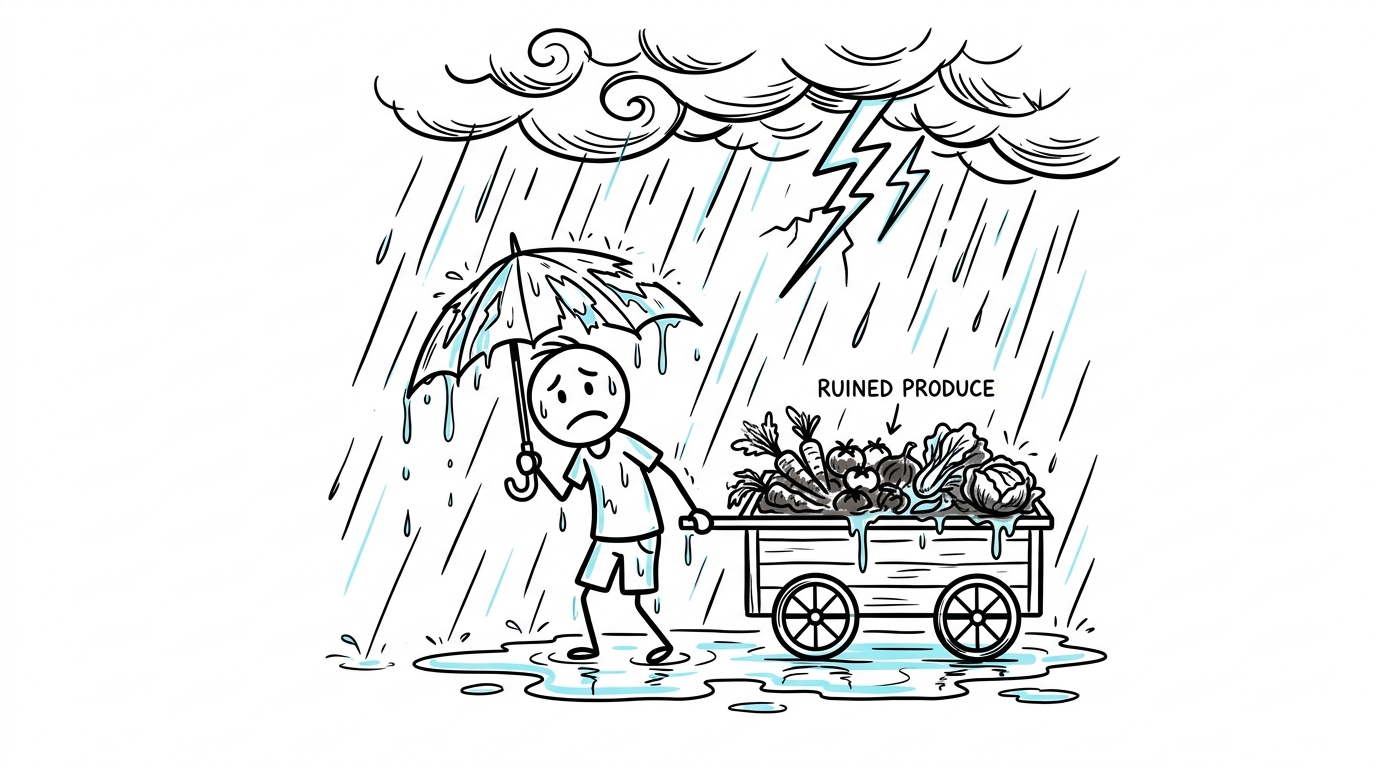
One monsoon flood = total income loss. Zero insurance. Zero safety net. Until now.
Inspiration
Every morning at 4:30 AM, 40 million informal street vendors across India face an invisible crisis — they need ₹3,000 for wholesale inventory before dawn, but have no access to formal credit. With nowhere else to turn, they pay loan sharks charging >300% APR. We asked: what if a vendor's own daily UPI sales could fund tomorrow's inventory automatically?
What it does
FinFlow (VyaparSetu) is an algorithmic daily micro-liquidity platform built on India's Digital Public Infrastructure (UPI + Aadhaar + DigiLocker).
- 🌅 Sunrise Capital — Auto-disburses ₹1,500–₹5,000 at 4:30 AM at a flat ₹20 fee (not 300% APR)
- 💸 Reverse Micro-Skimming — Recovers capital by deducting 5–10% from each incoming UPI payment throughout the day. No EMIs, no defaults.
- 🛡️ Parametric Climate Shield — Auto-pays ₹500–₹2,000 within 4 hours of a flood/heatwave event (IMD API trigger), no claims process
- 🪙 Suraksha Goolak — Builds a high-yield emergency buffer from micro-rounding on every transaction
How we built it
- Core Engine: UPI Split API + real-time cash-flow telemetry via IoT soundbox edge nodes
- Credit Scoring: Behavioral AI model on UPI velocity, inventory patterns, and climate risk — no CIBIL required
- Climate Layer: IMD (India Meteorological Department) API + parametric trigger logic
- Infrastructure: India's DPI stack — Aadhaar KYC, DigiLocker, UPI, AA Framework
- Pitch Stack: Interactive HTML/JS presentation, AI-generated stickman narrative visuals, synchronized voiceover video
Challenges we ran into
- Designing a repayment model that is frictionless for illiterate vendors — no app interaction required after setup
- Modeling parametric insurance triggers that are fair, auditable, and resistant to weather data manipulation
- Compressing a complex financial system into a 2-minute 22-second pitch that a judge understands instantly
Accomplishments
- Built a complete end-to-end system architecture covering credit, repayment, insurance, and savings — all in one daily UPI flow
- Unit economics that work: ₹20/day fee × 365 days = ₹7,300/year revenue per vendor with <2% default rate
- Scalable to 40M vendors = $3.5B TAM with zero marginal KYC cost via Aadhaar
What we learned
- India's DPI stack is the most underutilized fintech foundation in the world
- Behavioral cash-flow data is a superior credit signal to traditional CIBIL scores for informal merchants
- Parametric insurance is the only viable model for climate risk at the micro-merchant scale
What's next
- Partner with a NBFC for RBI sandbox approval
- Pilot with 500 vendors in a single mandi cluster in Delhi/Mumbai
- Expand climate shield to cover drought and crop failure for rural vendors
Built With
- aadhaar
- account-aggregator-framework
- avfoundation
- behavioral-ai
- digilocker
- edge-computing
- html
- imd-api
- india
- iot
- javascript
- parametric-insurance
- python
- upi

Log in or sign up for Devpost to join the conversation.