-
-
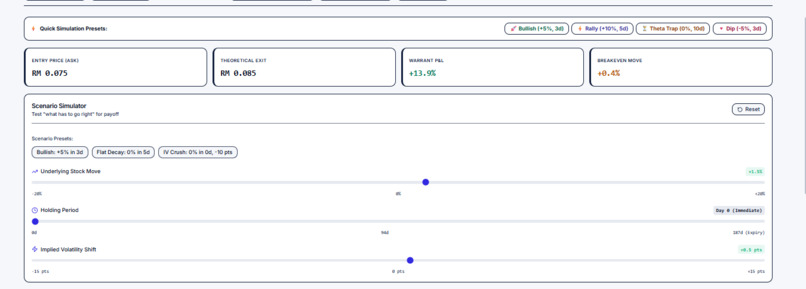
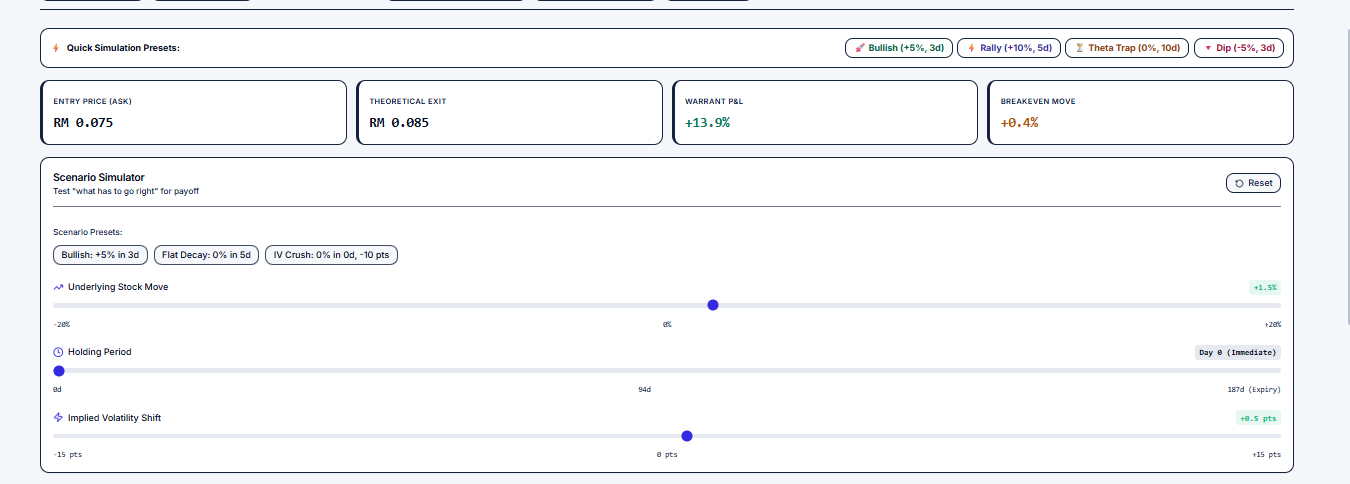
Scenario Simulation
-
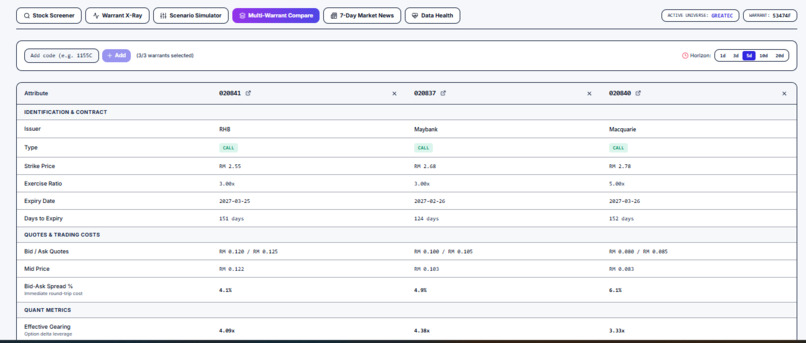
Warrant Comparison
-
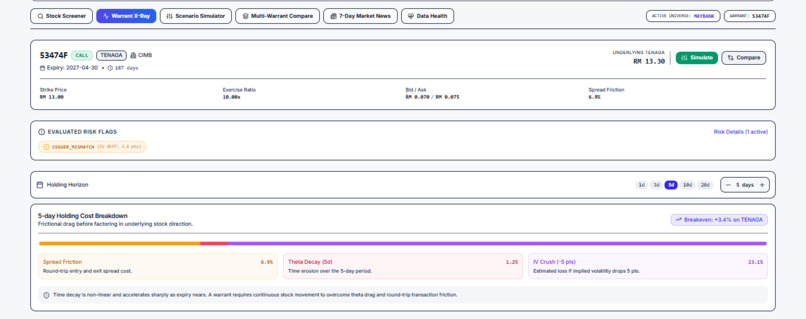
Analysis
-
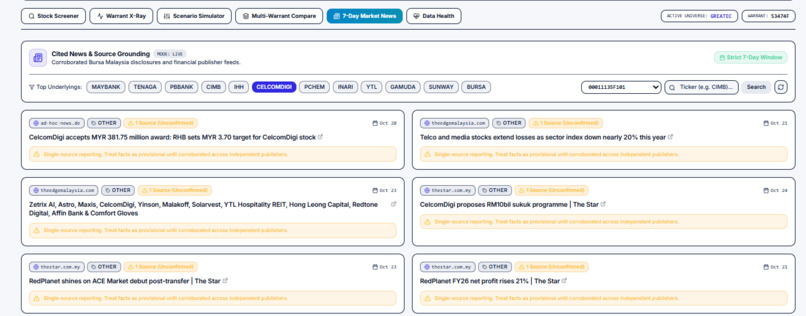
Real time News
-
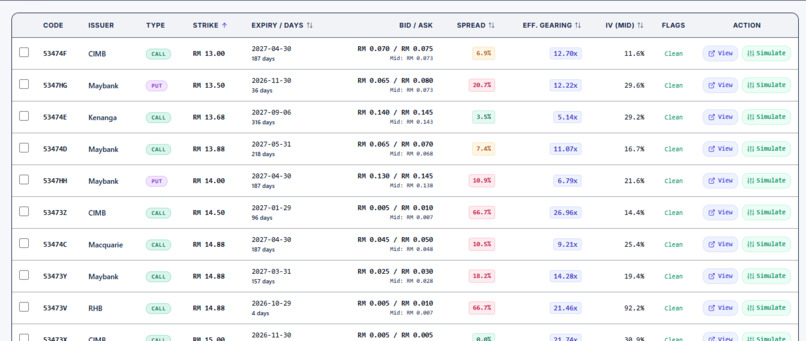
Warrant List Of Underlying Chosen
-
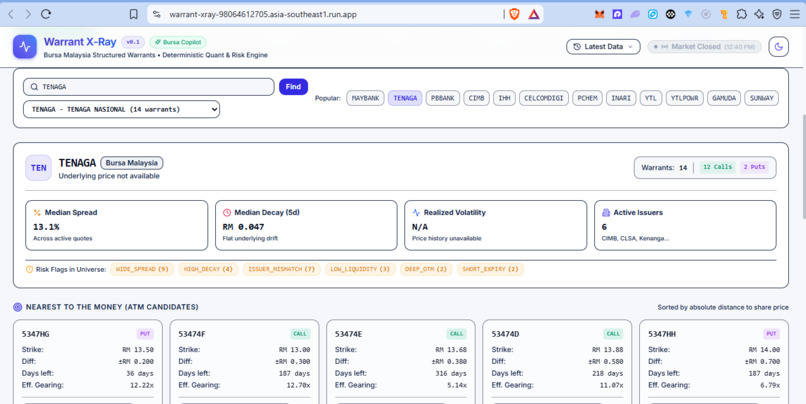
Underlying Stock
-
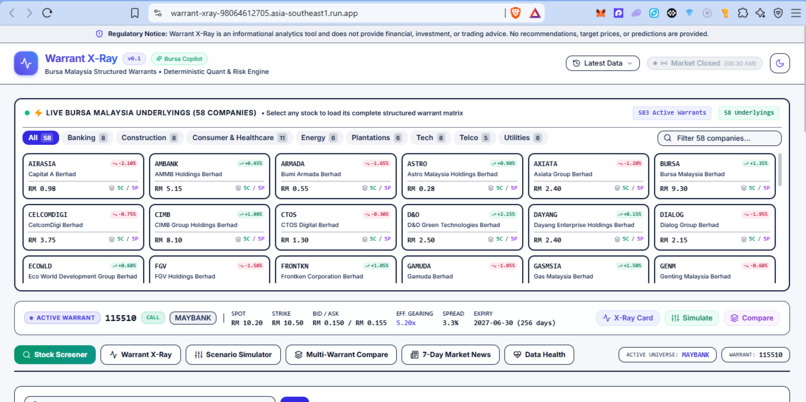
Home
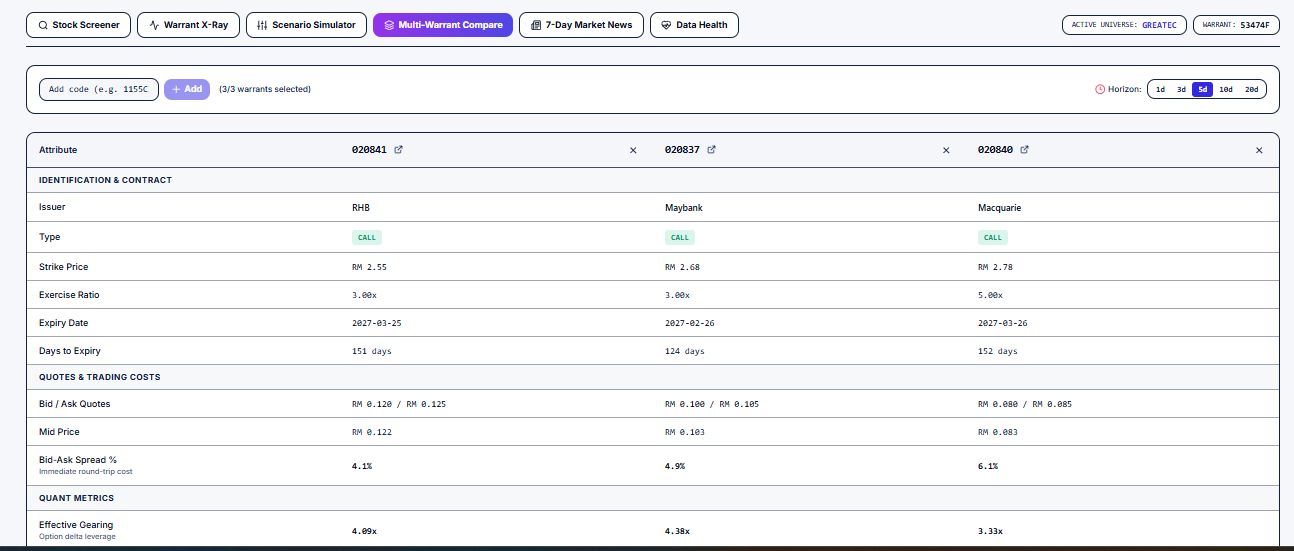
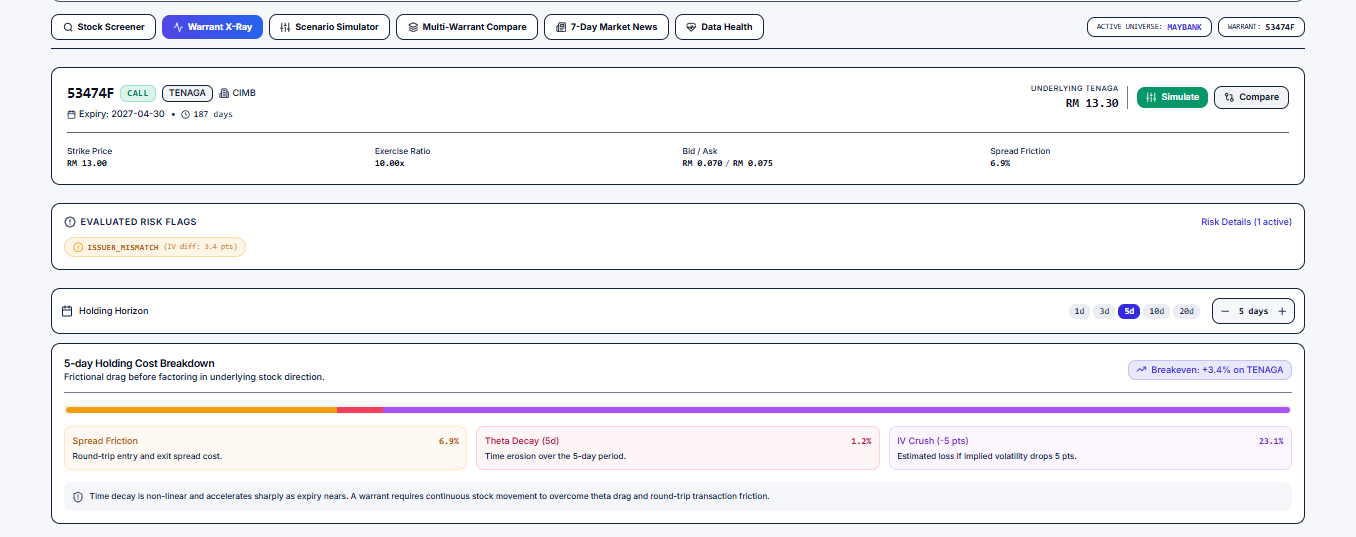
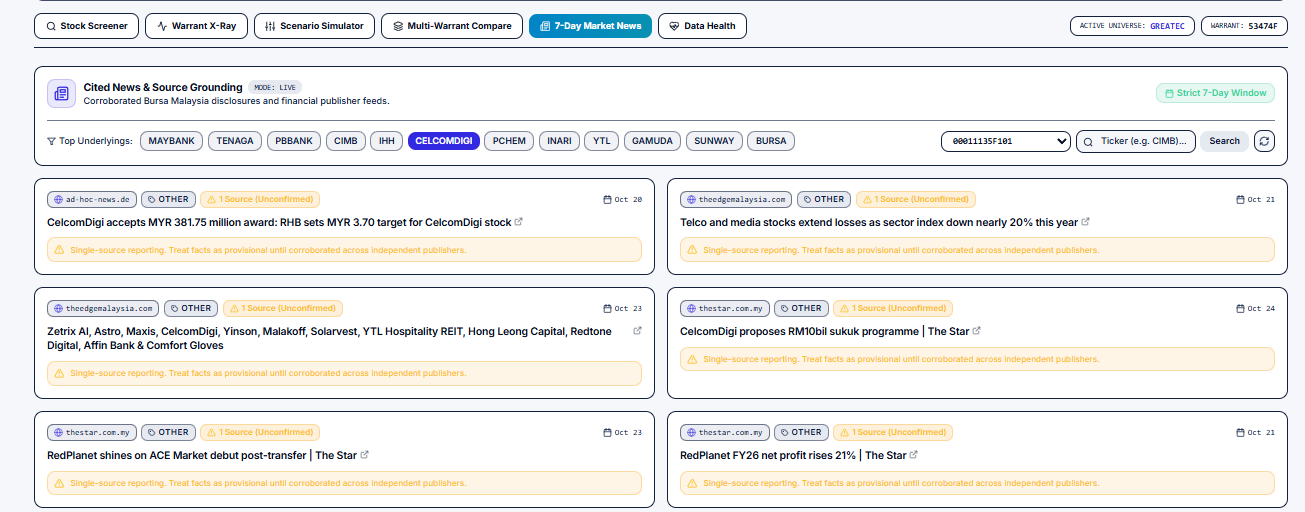
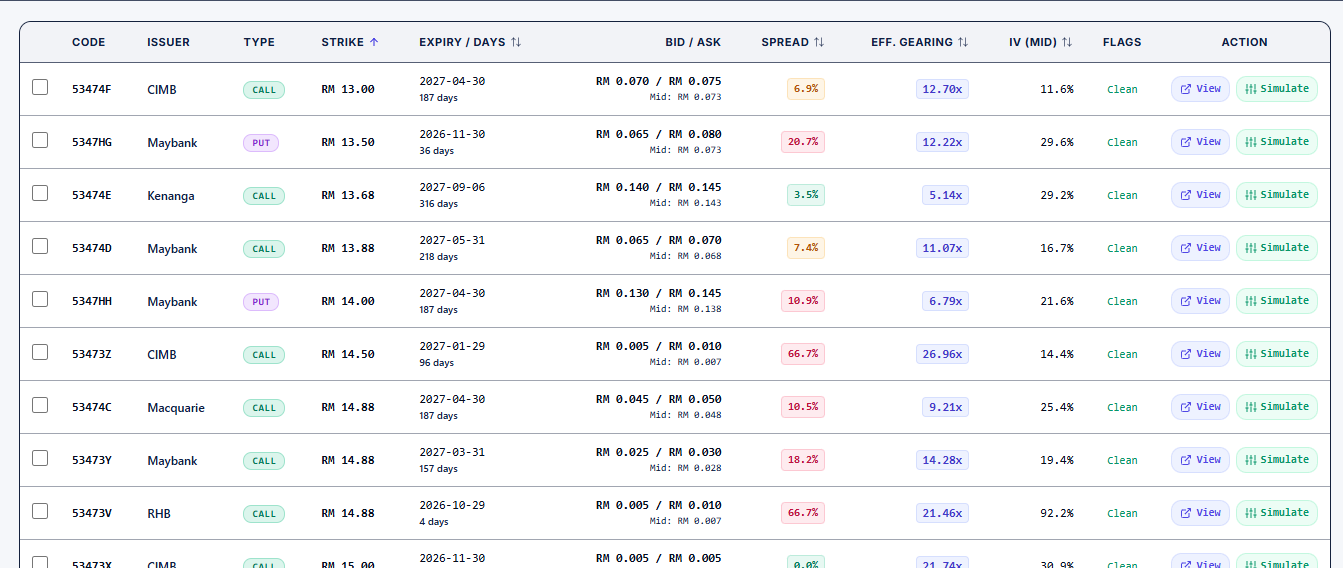
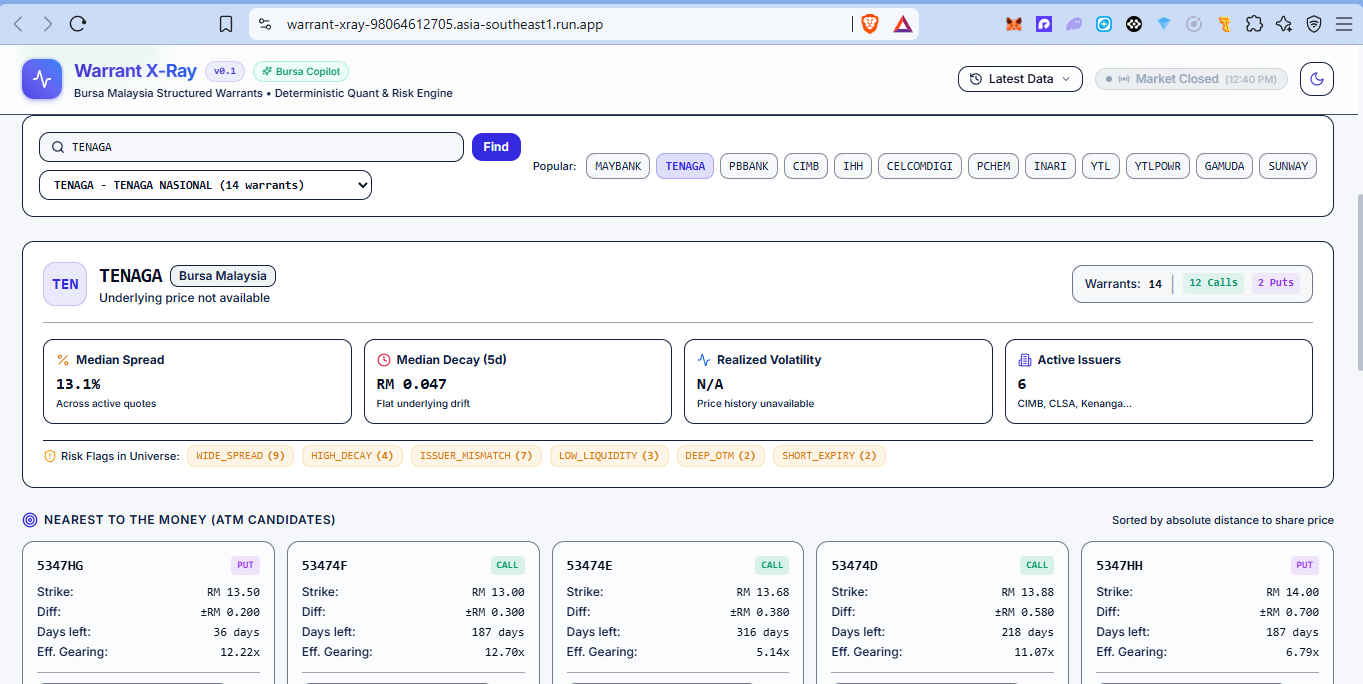
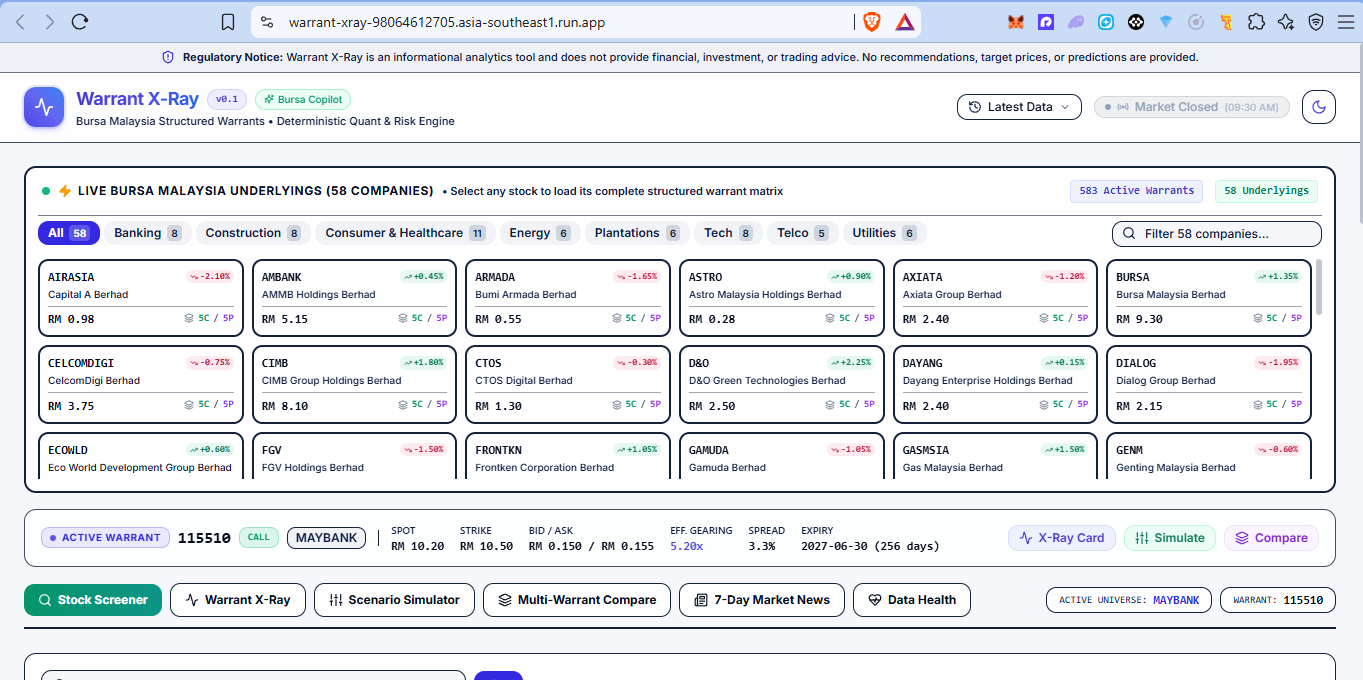
Warrant X-Ray: The Risk & Education Engine for Bursa Malaysia Structured Warrants
Inspiration
Like many retail traders on Bursa Malaysia, I was drawn to structured warrants for their capital efficiency and high leverage. But very quickly, my trading journey became an exhausting, costly nightmare: evaluating warrants manually was filled with hidden traps and misleading data.
My daily routine was painful and tedious. Whenever an underlying stock made a move, I would manually download warrant matrices, export spreadsheets from various issuer portals, and compare dozens of call and put contracts side-by-side to find the "cheapest" one with the best gearing.
That was when I discovered the critical flaw that cost me real financial losses:
The published Greeks were lying by omission.
On virtually every retail screener and issuer matrix, Theta (time decay) and Implied Volatility (IV) were only calculated against the last traded price.
In fast-moving Malaysian markets, an illiquid warrant's last trade might have happened hours ago—or even two days prior. Meanwhile, the actual live market bid and ask quotes had drifted significantly. When I bought at the live ask, the actual volatility I was paying for was drastically higher than the published matrix showed, and the true theta decay was far more punitive than my manual calculations predicted.
Relying on stale last-trade data led to severe miscalculations, ill-timed entries, and painful financial losses.
I realized that retail traders aren't failing because they lack market conviction—they fail because available tools fail to reflect real-time pricing mechanics. I built Warrant X-Ray to give retail investors the same multi-quote transparency, mathematical rigor, and real-time intelligence that institutional derivative desks take for granted.
What it does
Warrant X-Ray is an educational risk intelligence platform and interactive simulator for Bursa Malaysia structured warrants. Instead of giving speculative financial advice or black-box predictions, it answers the single question that matters most: "What does holding this warrant actually cost, and what has to go right for it to pay off?"
Key capabilities include:
- Multi-Quote Quantitative Recalculation: Independently recalculates Black-Scholes Greeks (Delta, Gamma, Vega, Theta, Effective Gearing) across Bid, Mid, and Ask quotes—eliminating the trap of relying on stale last-traded prices.
- Interactive Scenario Simulator: Allows traders to drag intuitive sliders to stress-test underlying stock moves (-20% to +20%), holding periods (0 to 60+ days), and volatility shifts (-15 to +15 pts), rendering dynamic P&L trajectory curves and exact breakeven hurdles.
- Automated Risk Flags: Immediately identifies red flags including wide bid-ask spread traps, zero-bid quotes, high time-decay erosion, approaching expiration, and issuer matrix discrepancies.
- Verified 7-Day Market Context: Integrates fresh, domain-filtered Malaysian corporate announcements and financial news to explain market sentiment without hallucinations.
(Note on Data Availability: Live real-time intraday exchange tick feeds from Bursa Malaysia are currently not connected in this release; the platform operates on comprehensive synthetic fixtures and historical snapshots to demonstrate the full quant engine and risk modeling safely.)
How we built it
Warrant X-Ray combines a zero-hallucination deterministic quant engine with state-of-the-art AI reasoning and search infrastructure:
NVIDIA Nemotron LLMs (Nemotron-3-Super, Nemotron-3-Super & Nemotron-3-Ultra):
- We leveraged NVIDIA's Nemotron architecture for our reasoning and synthesis layer.
- Nemotron-3-Super serves as the root orchestration engine, parsing user queries, selecting tools, and enforcing strict regulatory guardrails.
- Nemotron-3-Ultra powers our Deep Risk Reports, synthesizing complex multi-scenario derivative risks, issuer discrepancies, and corporate catalyst data into clear, actionable retail education.
- Nemotron-3-Nano powers our chats that provides basic info on warrants and links for detailed risk related information
- Deterministic Guardrail ("Verify-Before-Stream"): LLMs are strictly forbidden from calculating or rounding financial numbers. Every metric is computed by pure Python solvers and passed as immutable evidence pills into the Nemotron context window.
Ultra-Low-Latency Nebius Inference:
- All Nemotron models are served via Nebius Token Factory, providing enterprise-grade, ultra-low-latency GPU inference.
- Nebius enables high-throughput token generation with deterministic temperature control, ensuring fast response times while preserving mathematical rigor and zero drift during structured risk breakdowns.
Tavily Search API (Warrant search &7-Day Recency & Source Verification):
- As new warrants are created on daily basis, Tavily performs agentic search to retrieve the information of the newly created warrants.
- Derivative pricing without news context is blind, but generic search engines return outdated or hallucinated articles.
- We integrated Tavily Search with a strict 7-day recency window, explicitly configured to crawl and search top Malaysian financial and regulatory domains (The Edge Malaysia, Bursa announcements, StarBiz).
- Every corporate claim surfaced by Warrant X-Ray includes an audited citation URL and exact retrieval timestamp.
Full-Stack Architecture:
- Backend: FastAPI with async Python, SQLite persistence via SQLAlchemy and aiosqlite, and pure Python/SciPy Black-Scholes and Brent root-finding IV solvers.
- Frontend: Vite + React 18 SPA built with Tailwind CSS, Lucide icons, and Recharts for fluid, accessible P&L curve visualization.
- Deployment: Multi-stage Dockerized build deployed serverless on Google Cloud Run in
asia-southeast1(Singapore) for low-latency delivery across Southeast Asia.
Challenges we ran into
- The Stale Price Trap: Translating the manual pain of last-trade distortion into an automated multi-basis solver was complex. We had to build custom Brent root-finding solvers that handle edge cases—such as zero bids, crossed quotes, and deep out-of-the-money options where standard solvers fail to converge.
- Constraining LLMs from Doing Math: Large Language Models naturally attempt to round decimals or perform mental math, which is fatal in financial derivatives. We had to design an uncompromising "Verify-Before-Stream" pipeline where the Nemotron models strictly interpret pre-computed evidence objects without modifying a single digit.
- Search Precision on Malaysian Financial Data: Standard web searches often surfaced generic global results or months-old articles. Fine-tuning Tavily queries with strict domain whitelisting and 7-day recency filters was essential to ensure retail traders receive timely, locally relevant Bursa context.
- Packaging Complex Derivatives Visually: Converting multi-dimensional option Greeks (Gamma, Vega, Theta decay over calendar days) into an intuitive, accessible slider interface that beginners can understand in seconds required dozens of design iterations.
Accomplishments that we're proud of
- Solving a Real Trader Pain Point: Transformed a manual, 30-minute Excel ordeal into an instantaneous, automated risk analysis that updates dynamically across live bid and ask spreads.
- Zero-Hallucination Derivative Analytics: Achieved an architecture where 100% of mathematical figures displayed on the UI and cited by the AI come from deterministic formulas, backed by unit tests verified against golden Black-Scholes values and put-call parity.
- Seamless Cloud Run & Nebius Integration: Achieved sub-second inference latency by coupling Nebius-hosted Nemotron models with a serverless Google Cloud Run backend.
- End-to-End Responsive Experience: Built a unified SPA with dark mode, accessible Recharts payoff curves, and real-time scenario simulation that runs smoothly on desktop and mobile browsers.
What we learned
- Derivatives Education Needs Tools, Not Advice: Retail traders don't need a bot telling them what to buy; they need an x-ray showing them what a trade actually costs if the underlying stock moves sideways for five days.
- The Power of Specialization (Nebius + Nemotron + Tavily): Pairing specialized GPU inference on Nebius with purpose-built search infrastructure like Tavily outperforms one-size-fits-all generic LLM APIs in domain-specific finance applications.
- Quotes Matter More Than Trades: In leveraged structured warrants, the current bid-ask spread is reality—the last traded price is just history. Designing our architecture around multi-quote recalculation was the single most impactful technical decision.
What's next for Warrant X Ray
- Live Bursa Malaysia Direct Feed Integration: Transitioning from historical snapshots and synthetic fixtures to real-time Bursa Malaysia websocket streaming feeds for tick-by-tick Greeks recalculation.
- Portfolio & Multi-Leg Holding Tracker: Enabling traders to track multiple warrant positions simultaneously and visualize aggregated daily theta decay across their portfolio.
- Automated Matrix Arbitrage Detector: Continuously cross-referencing live market maker quotes against issuer-published matrices to flag mispriced warrants and spread widening events in real time.
- Mobile Native Companion App: Expanding beyond the web SPA into lightweight iOS and Android native apps for on-the-go Bursa warrant traders.

Log in or sign up for Devpost to join the conversation.