-
-
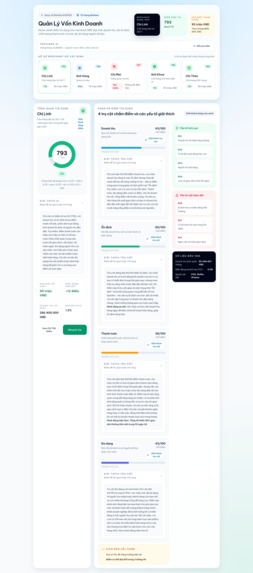
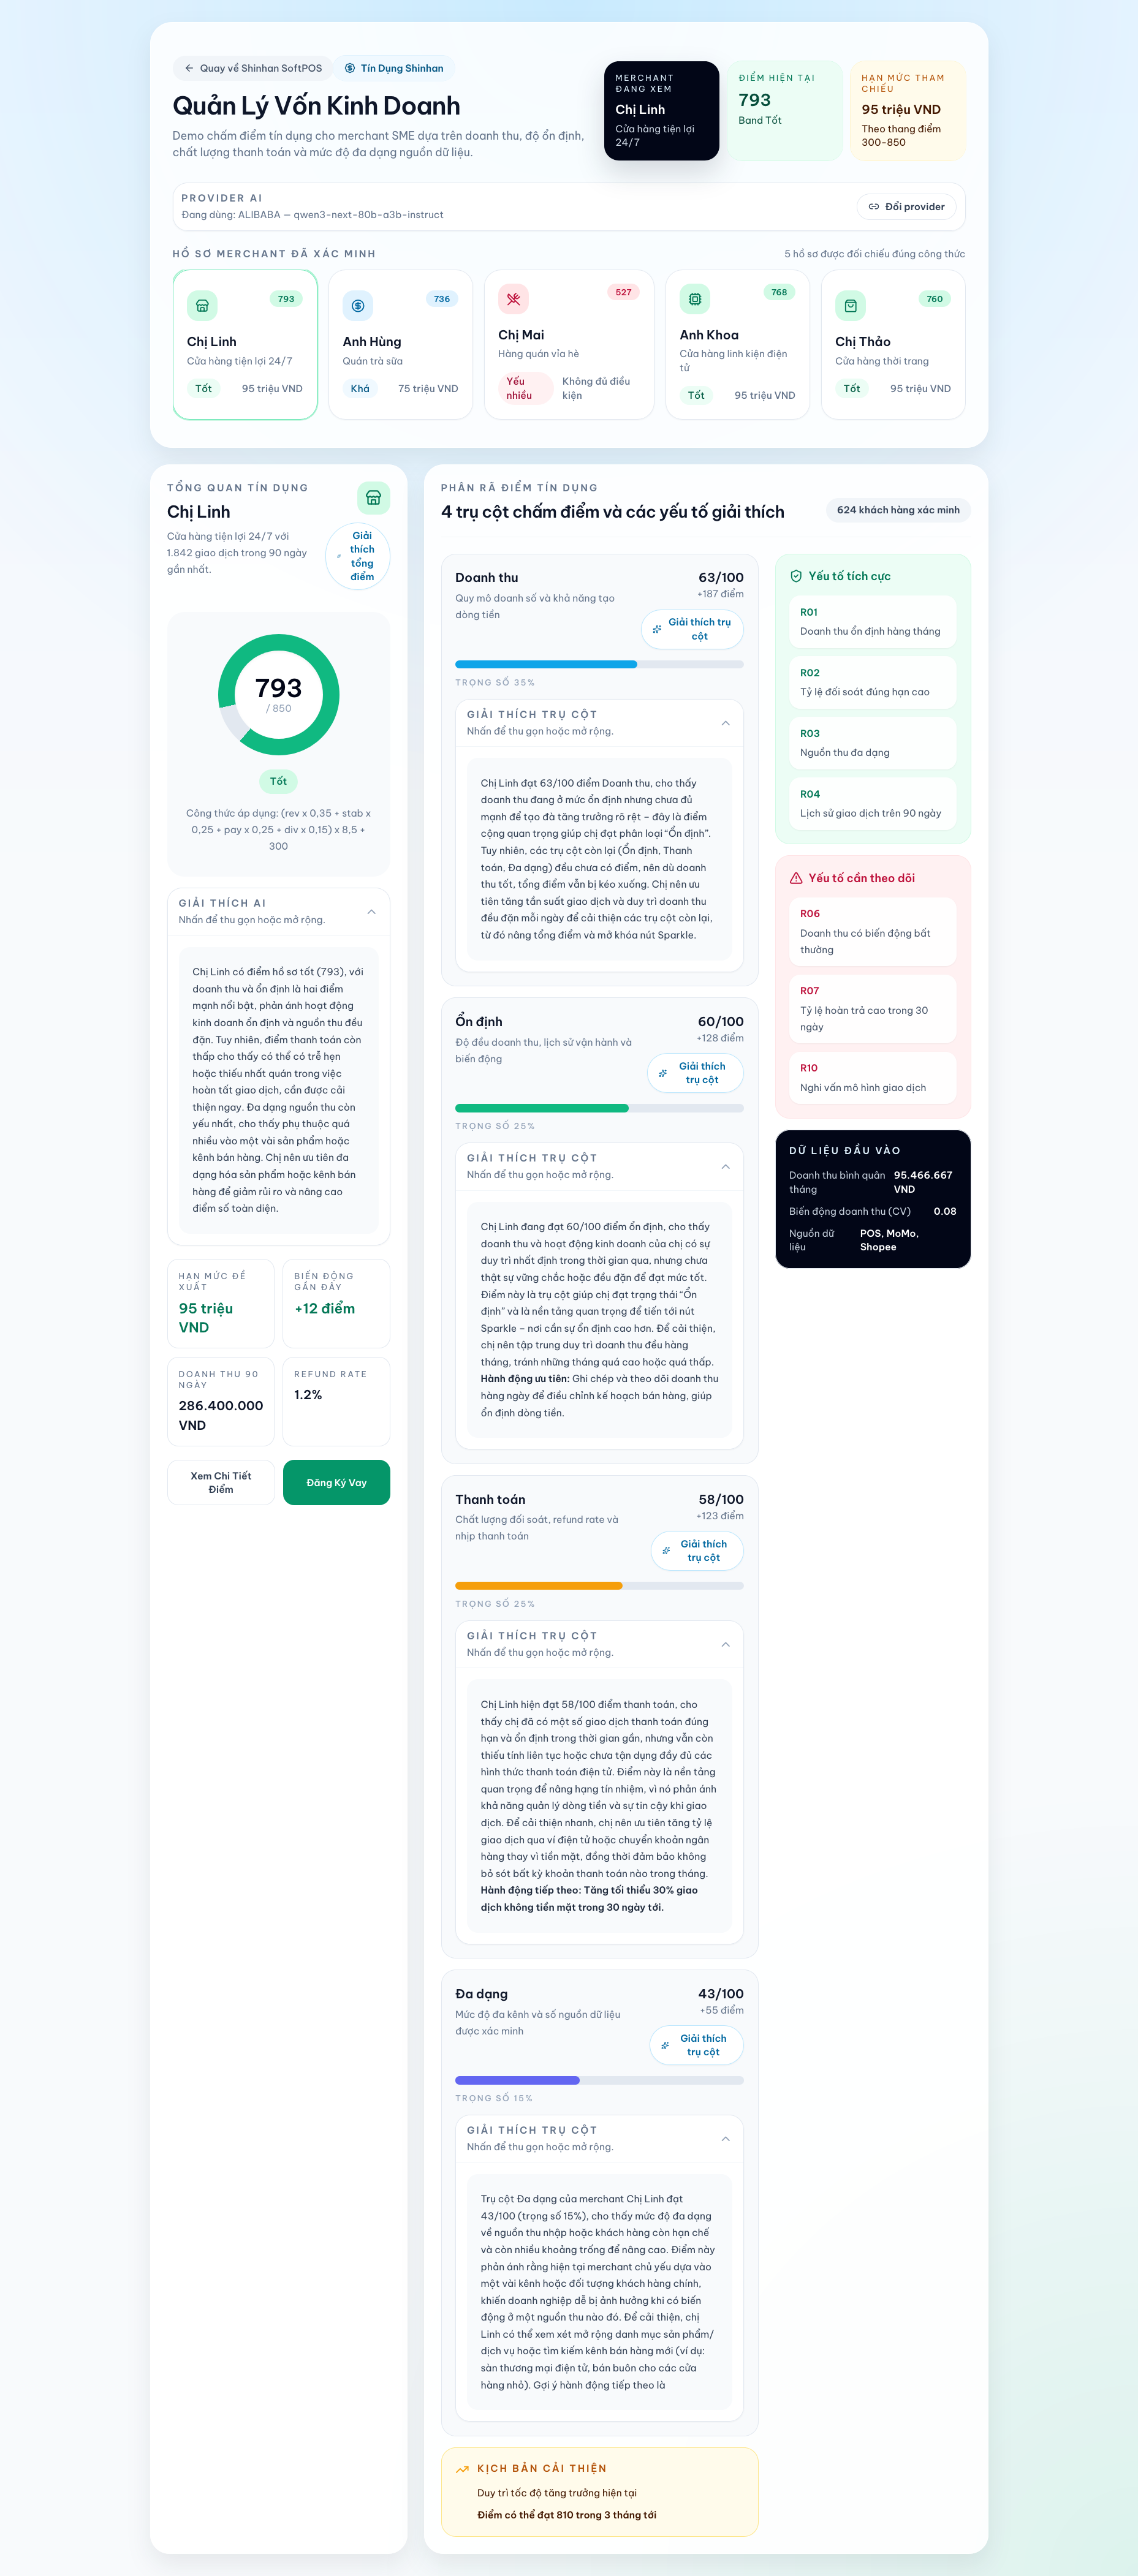
Lending analytics
-
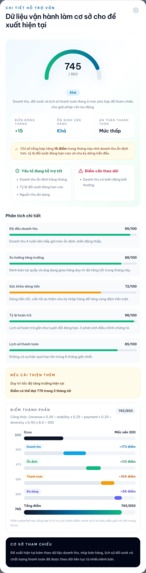
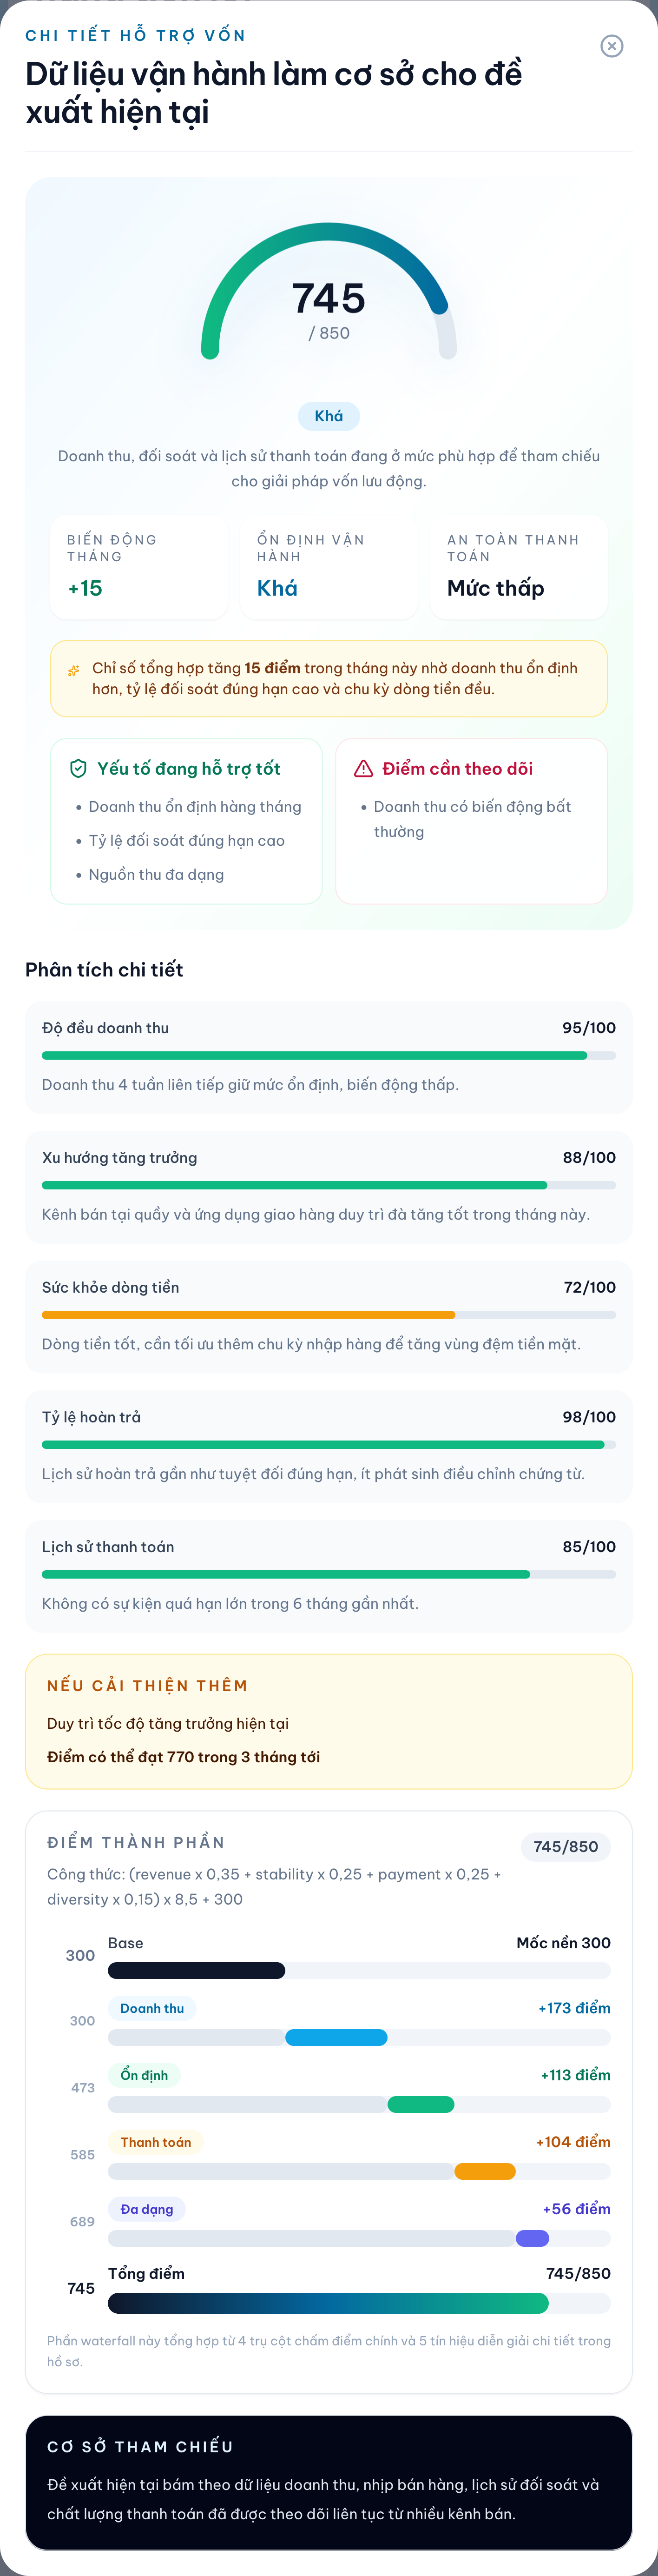
SME rating gauge
-
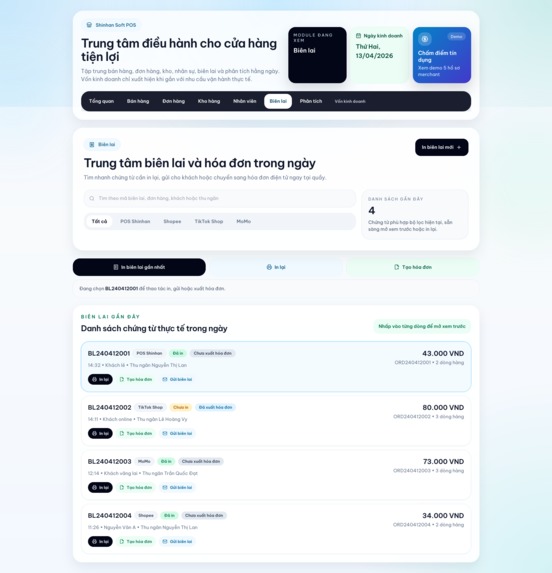
Bill management
-
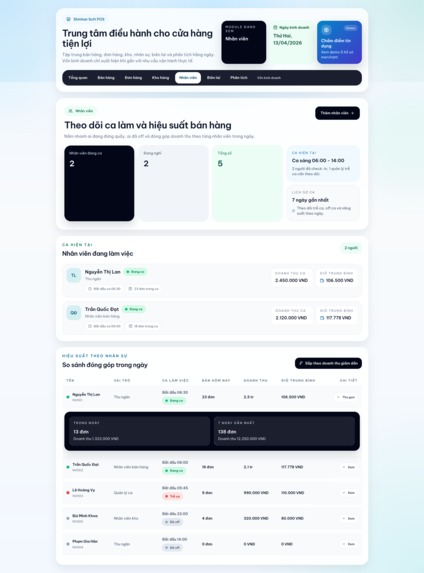
Employee management
-
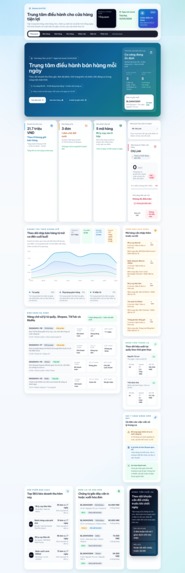
Home page
-
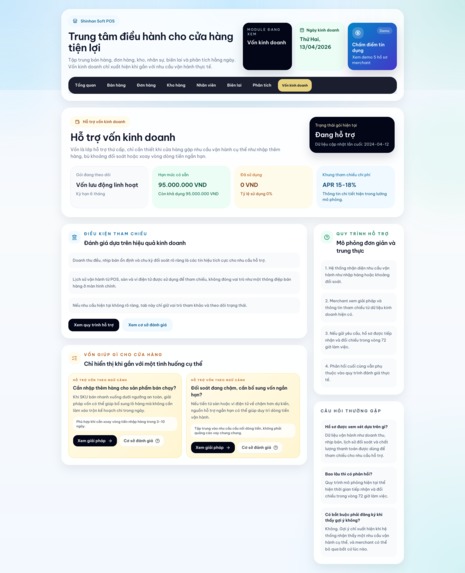
Loan
-
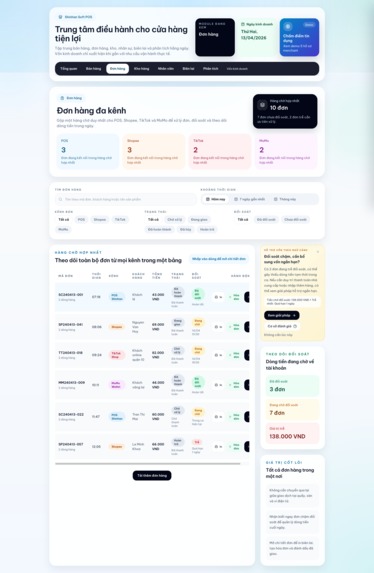
Order management
-
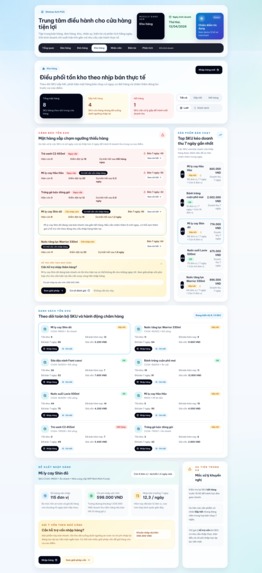
Warehouse management
-
human's cleverness wins limitations
-
Vibe coding? I vibe engineering, took 10 years to fix, which is fine, job secured!
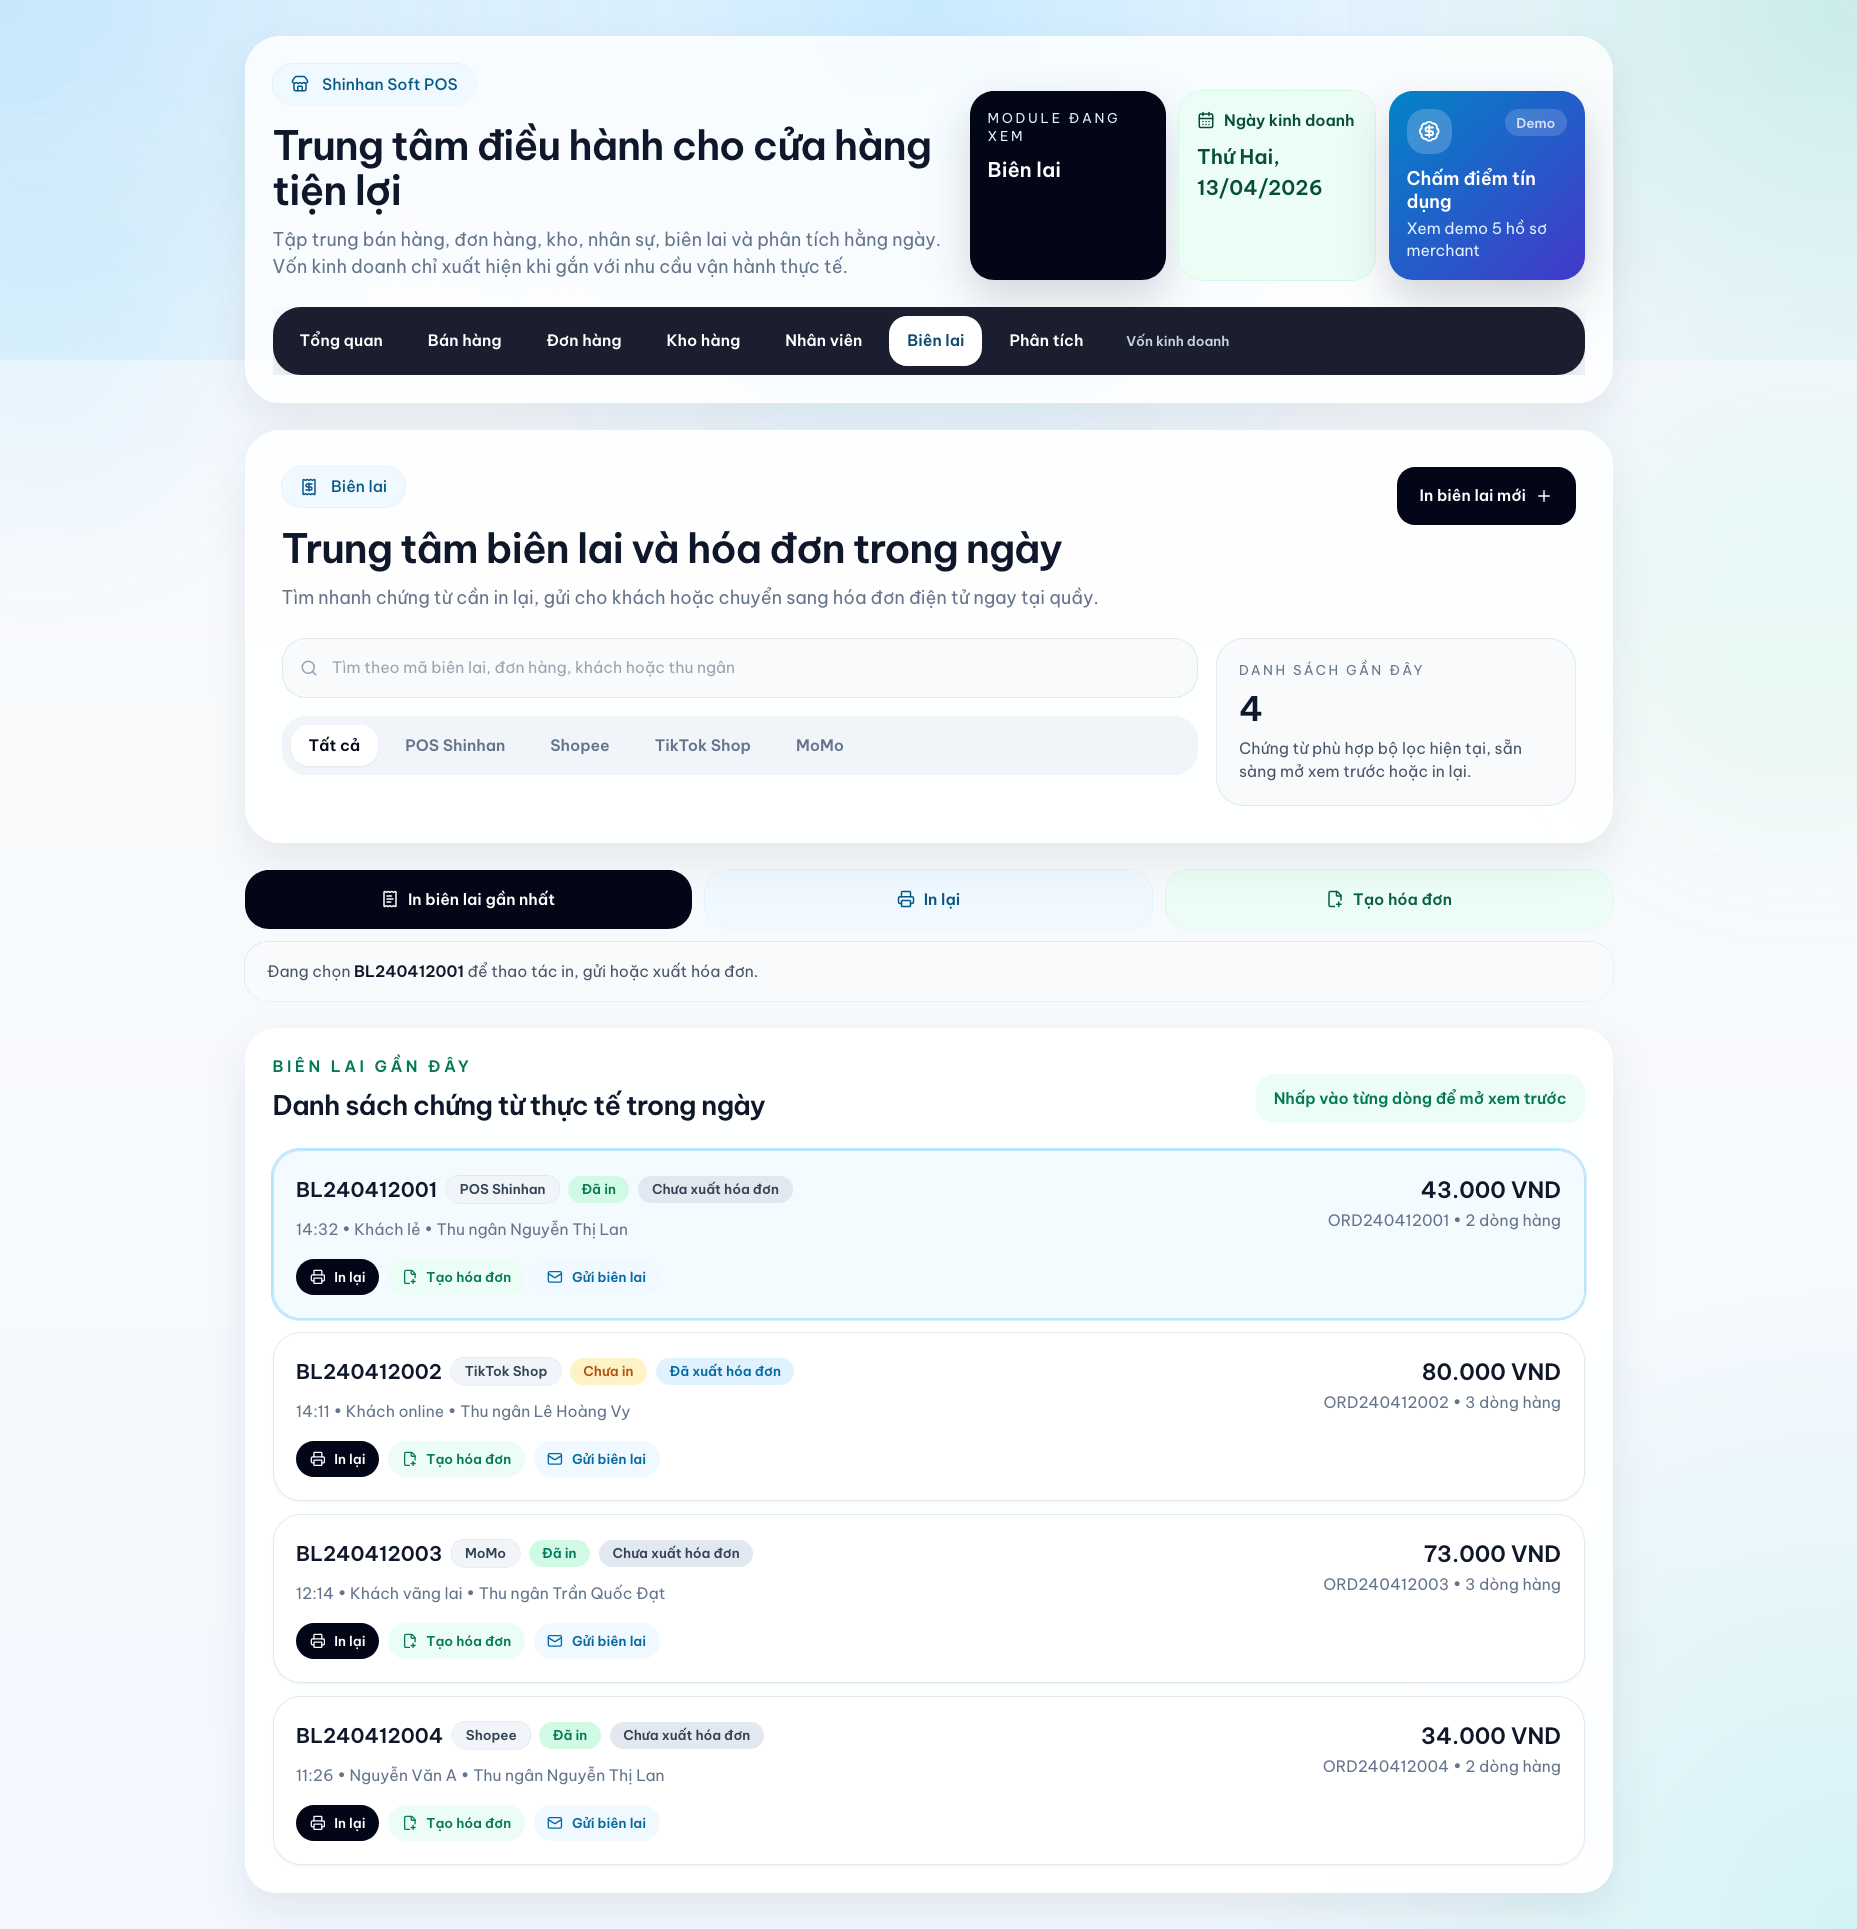
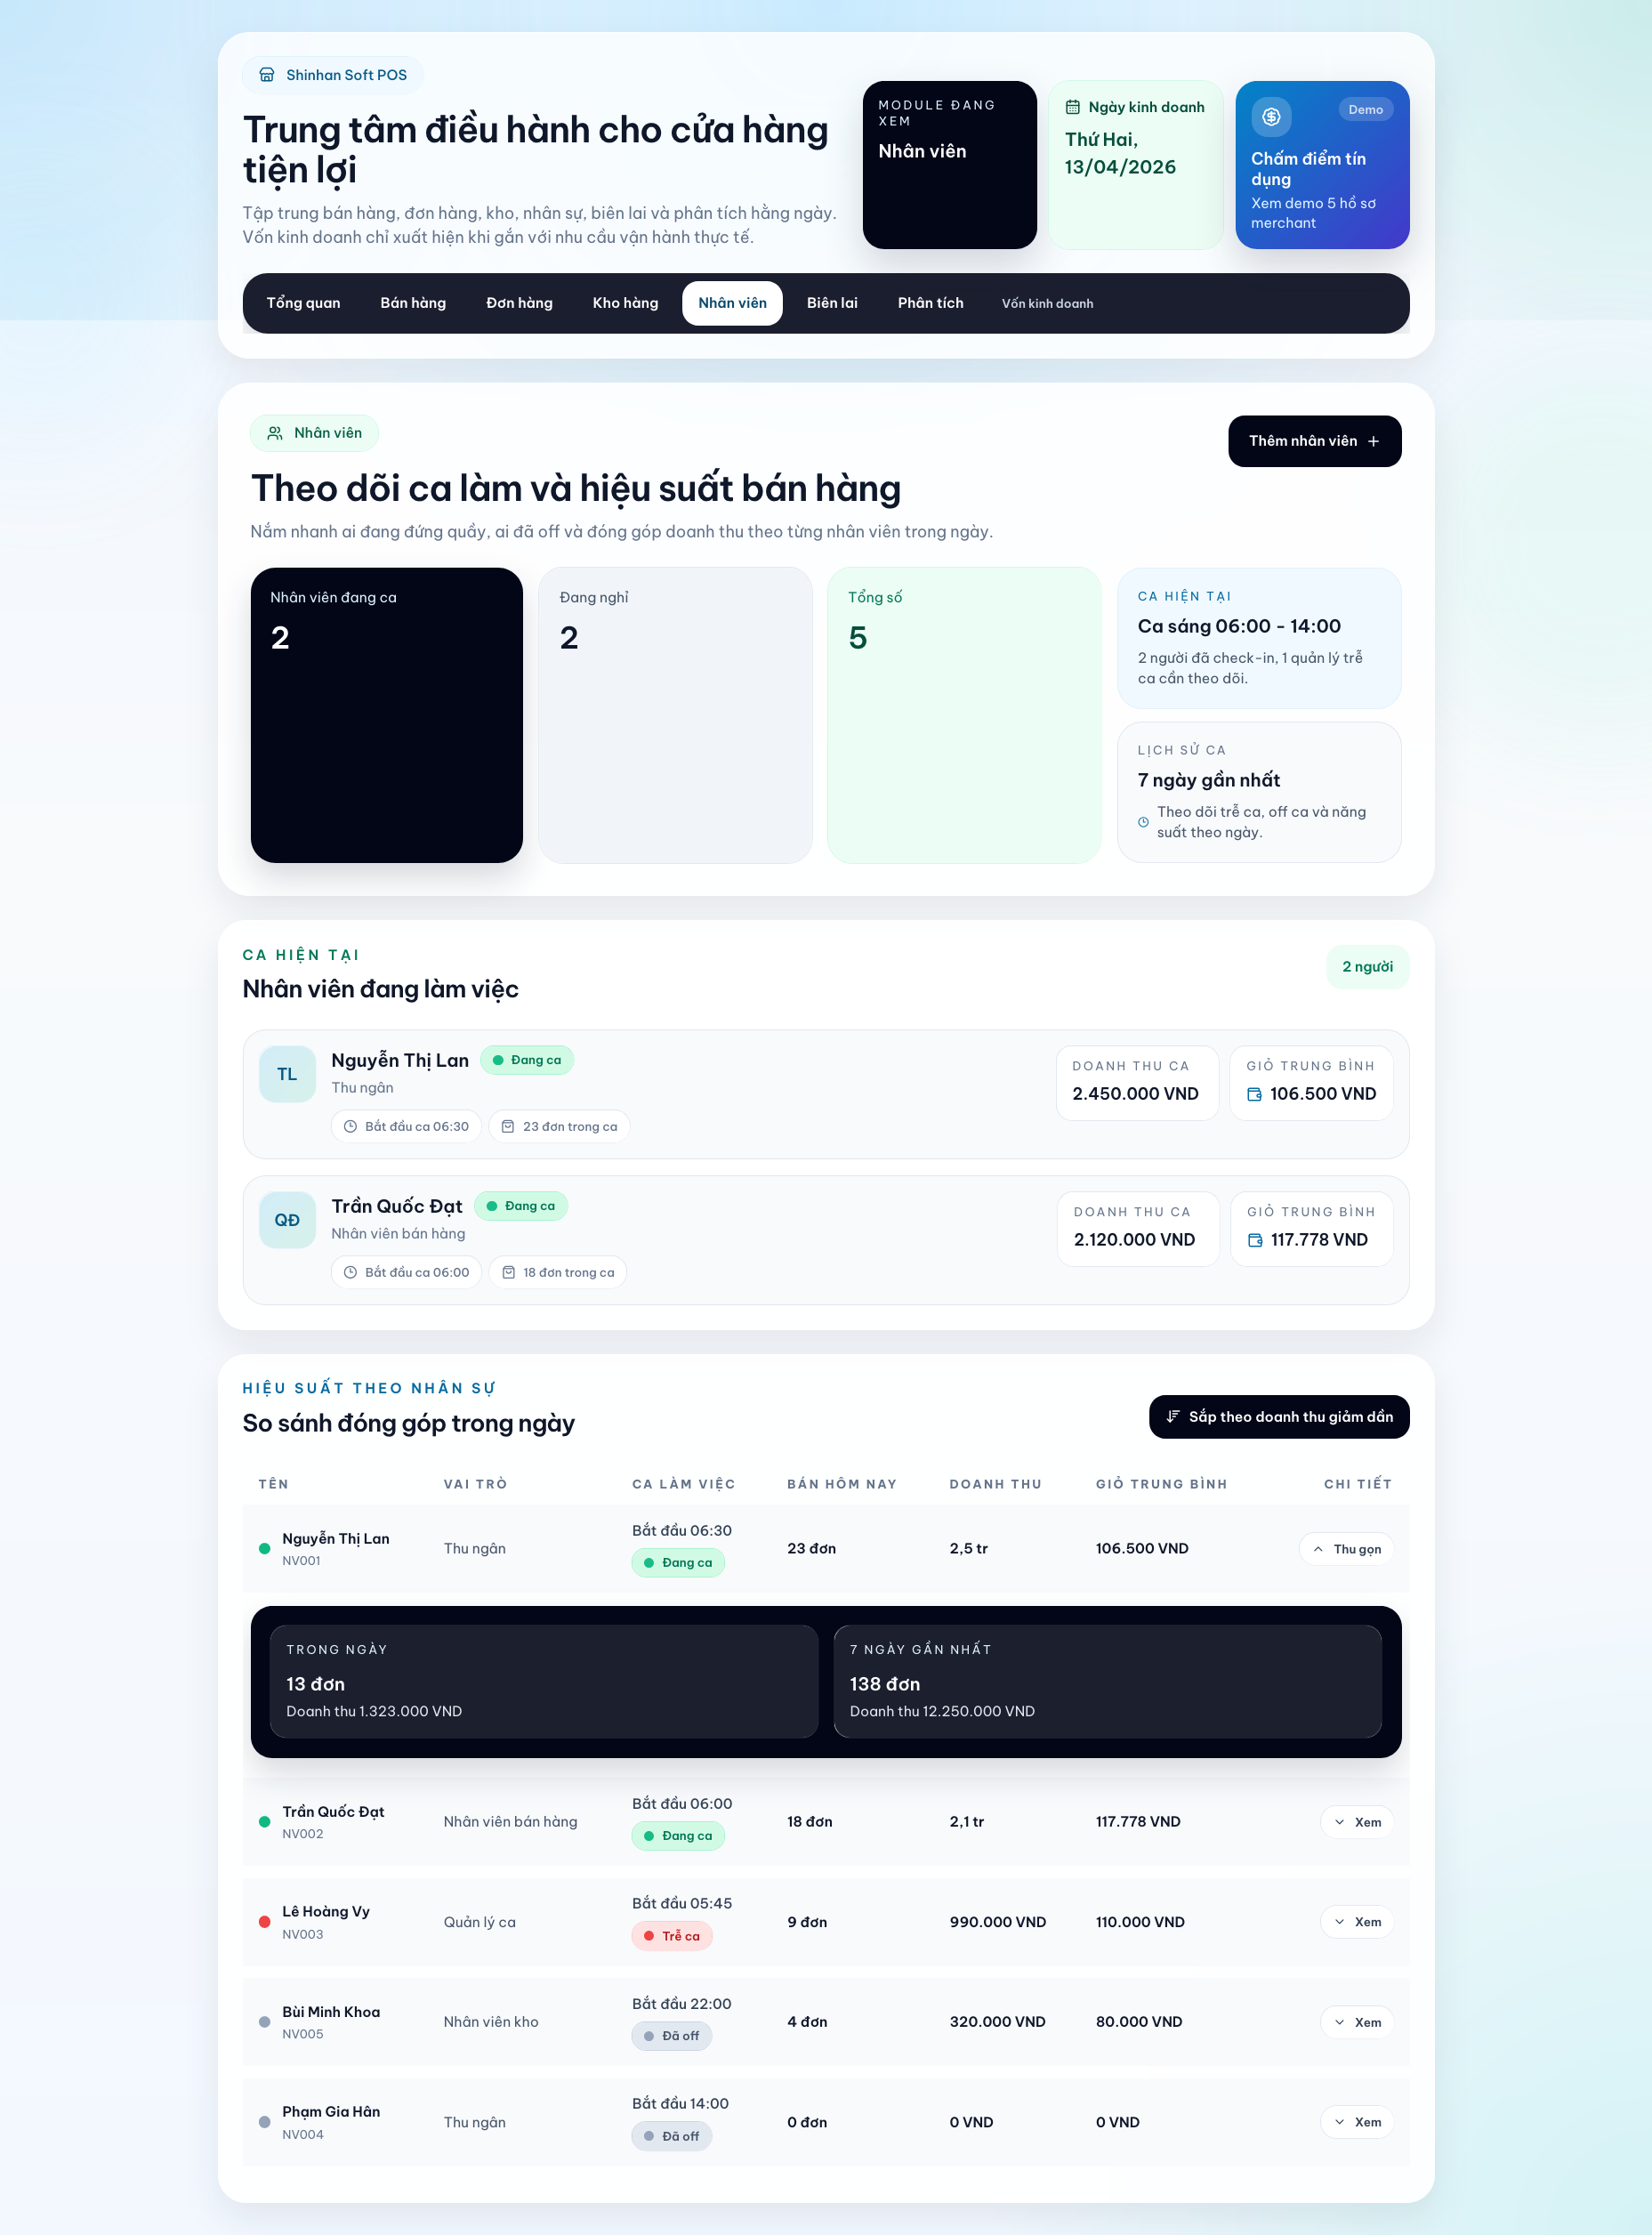
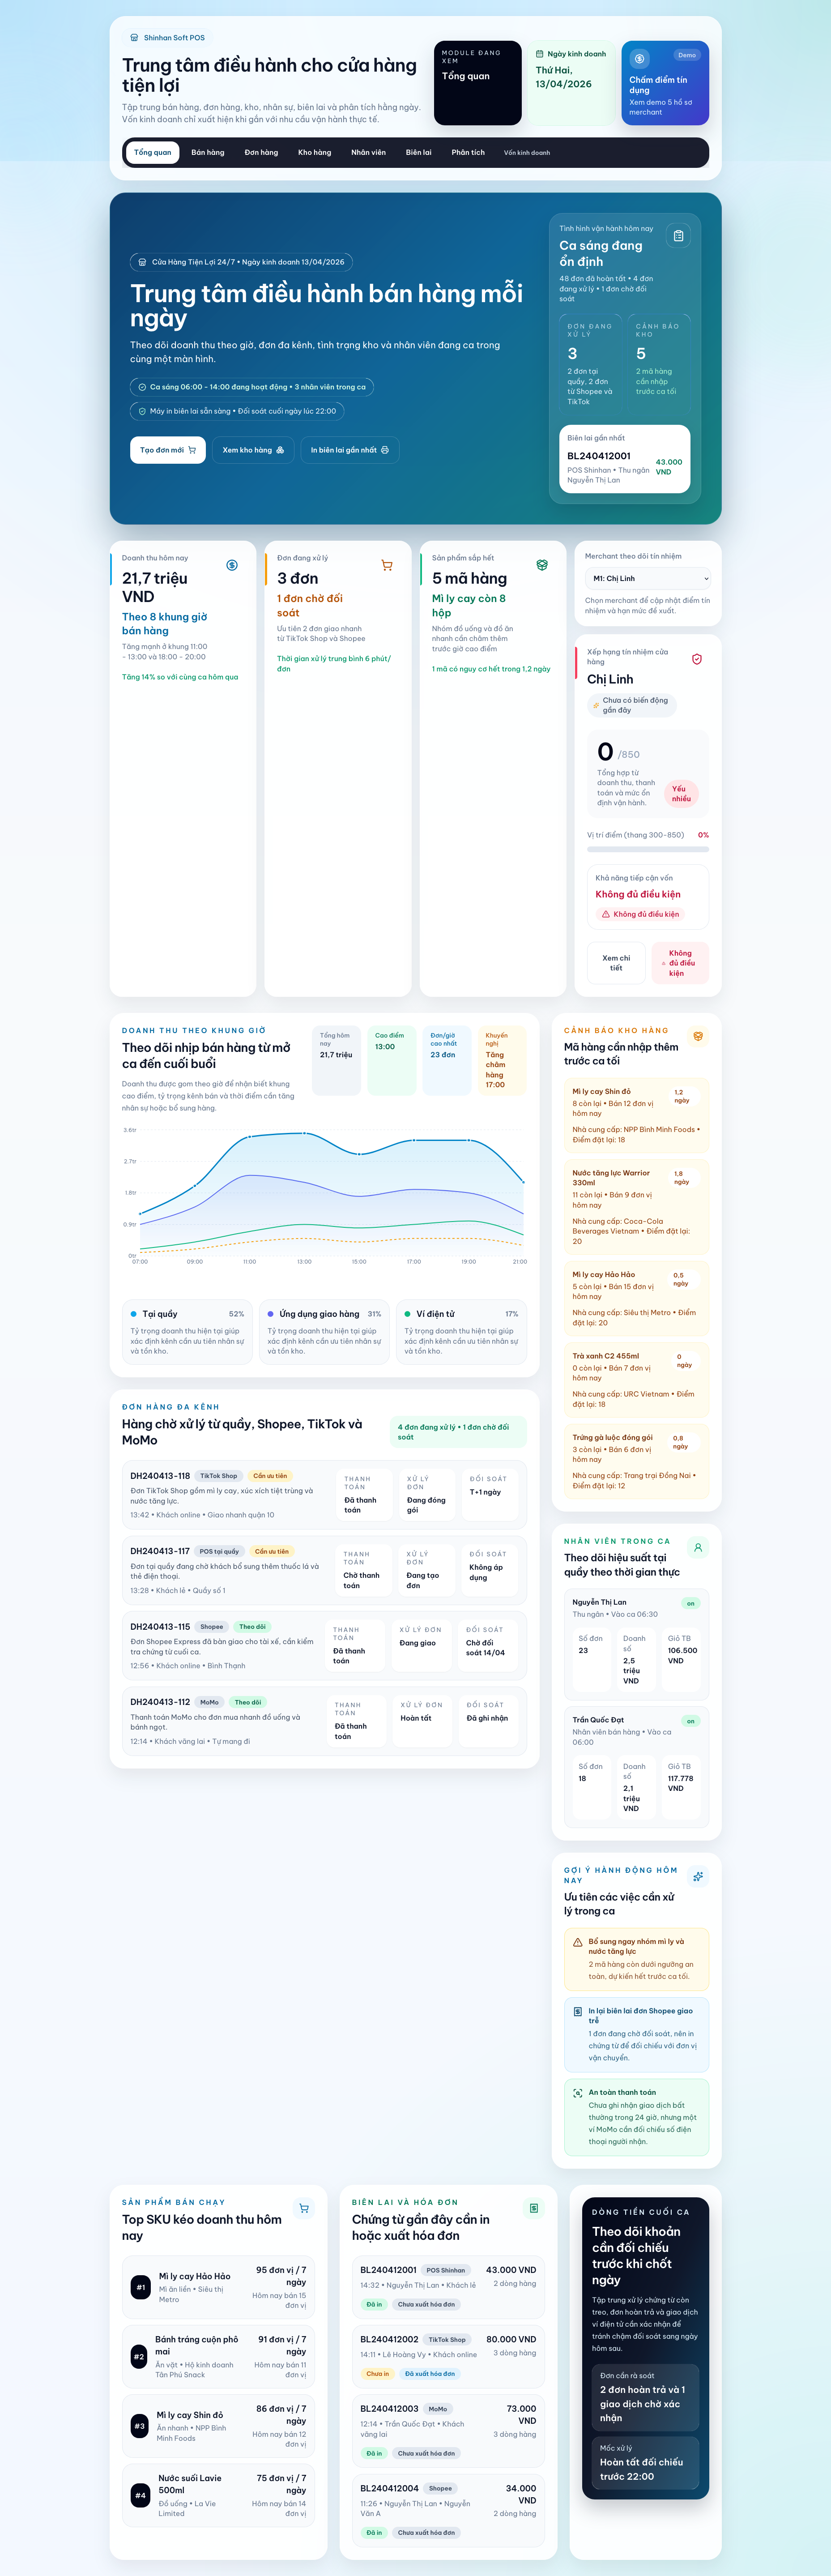
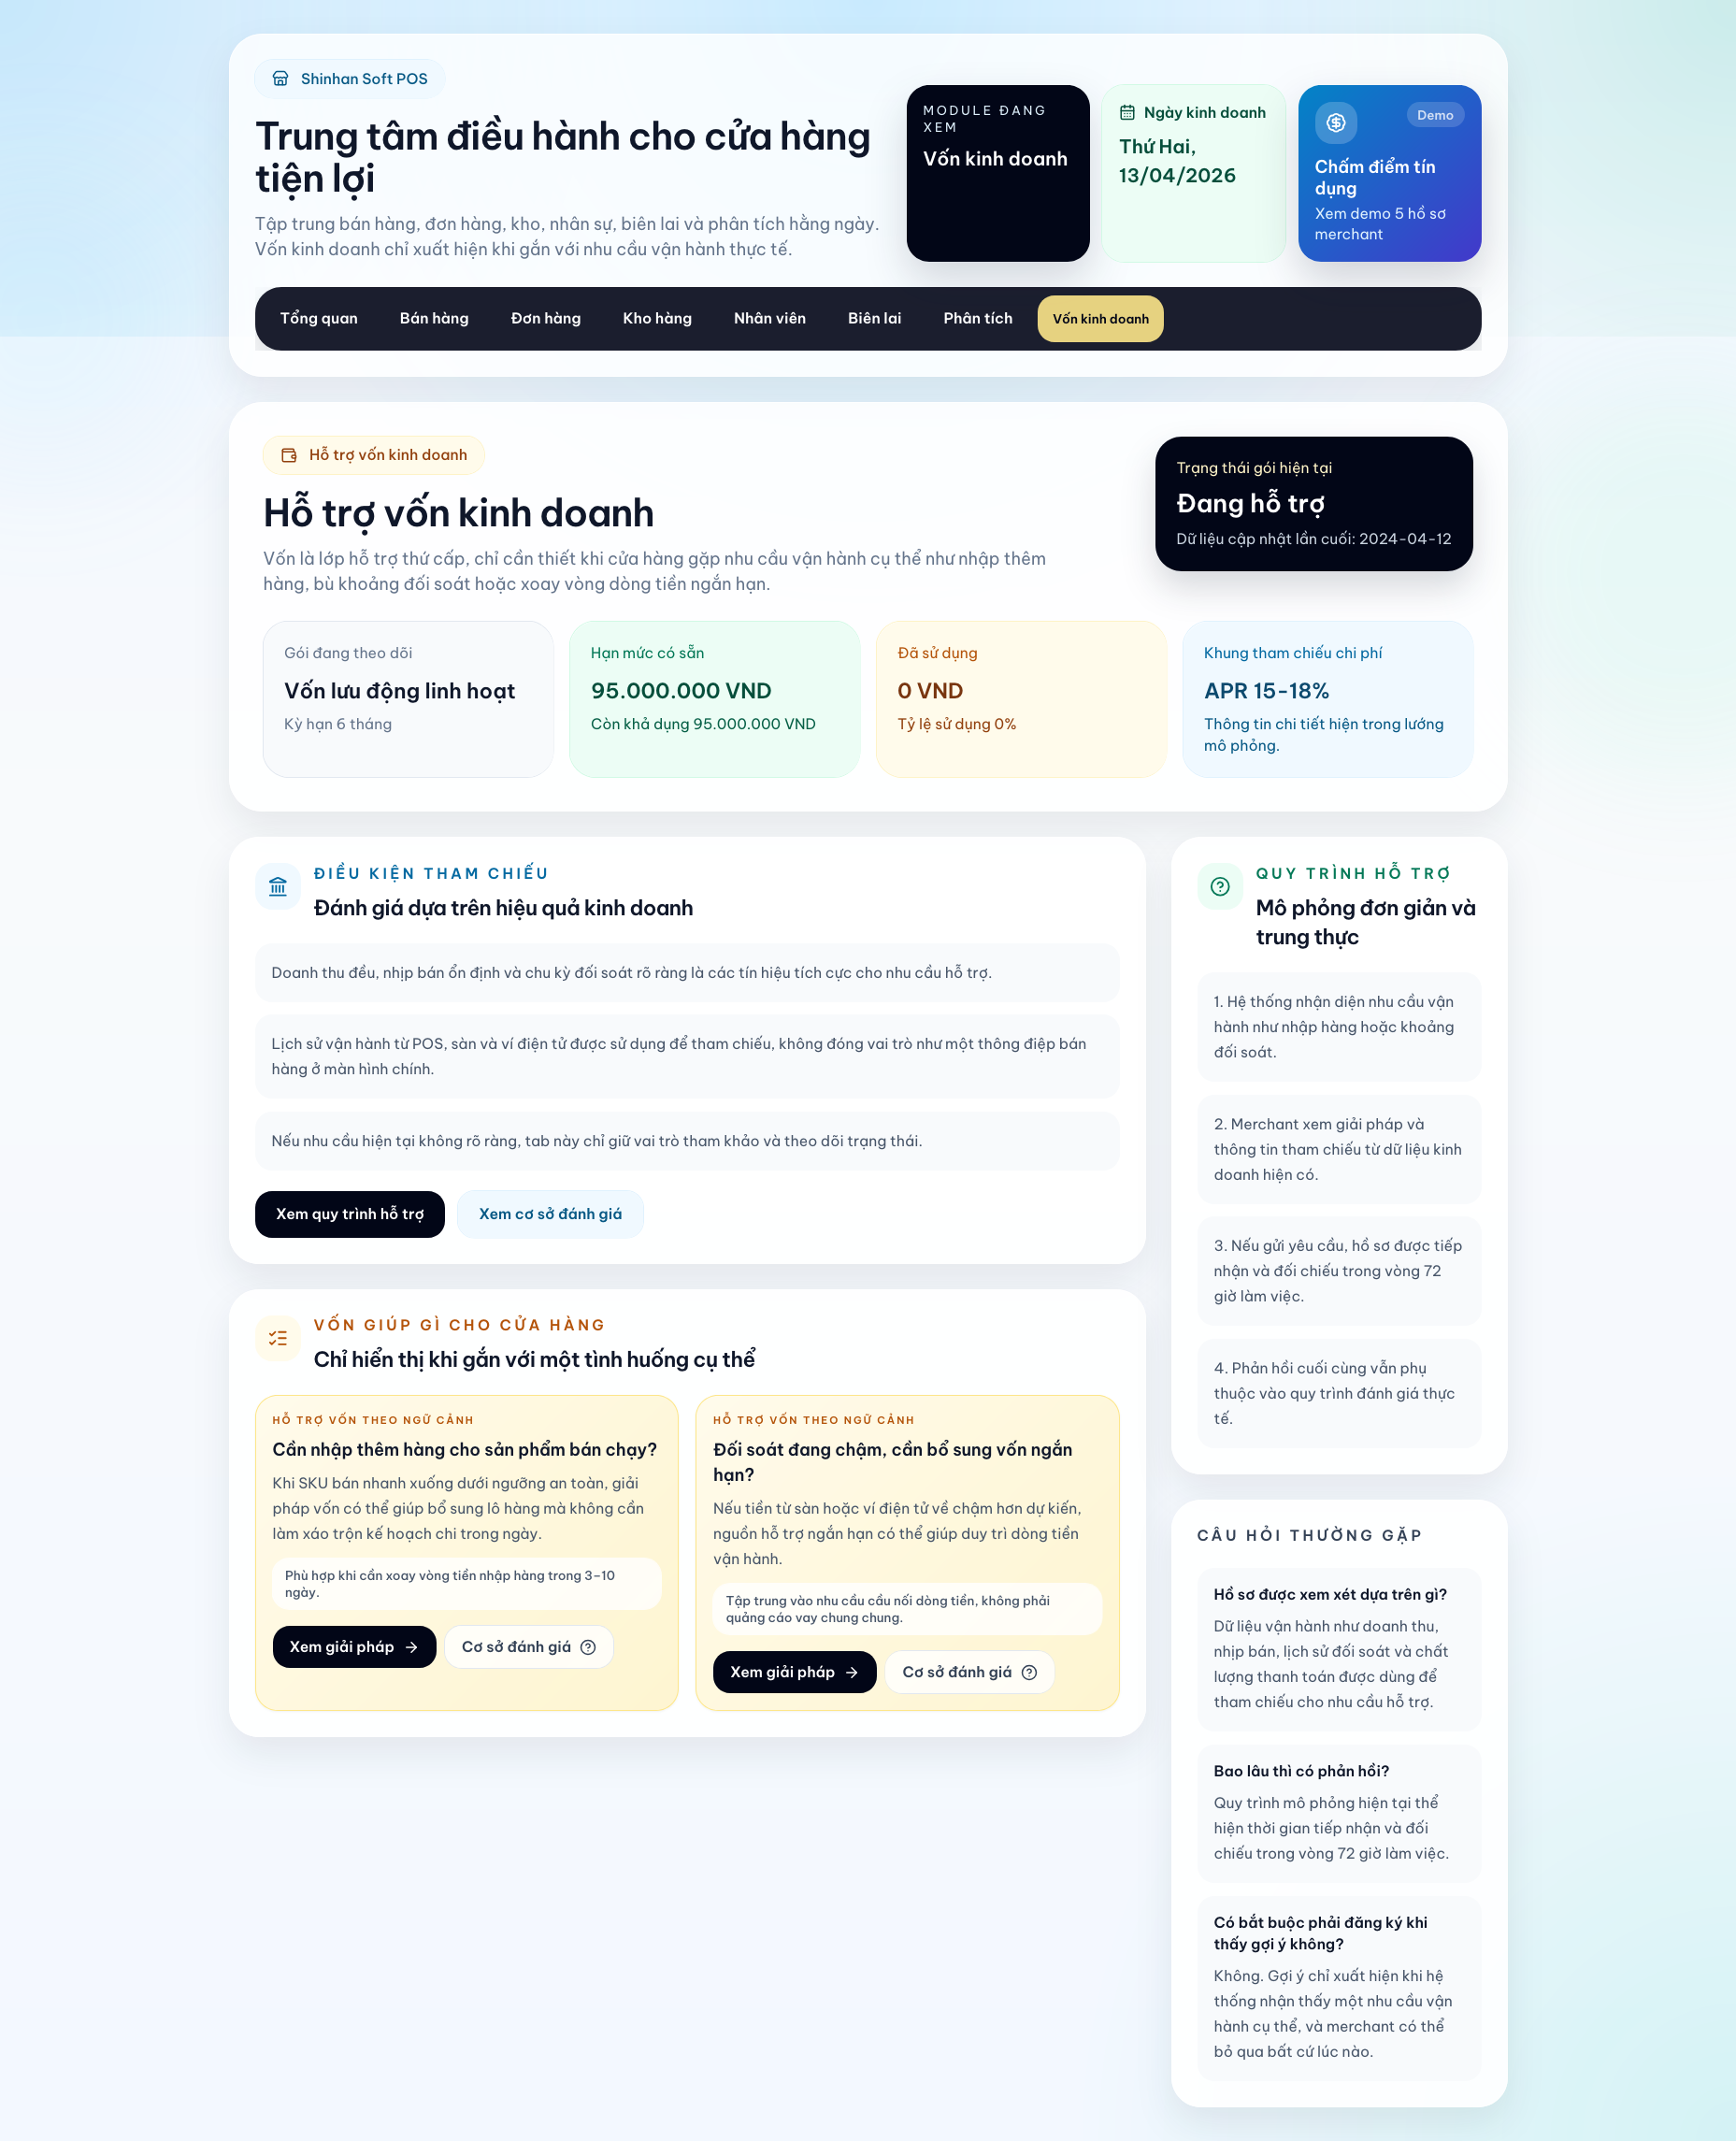
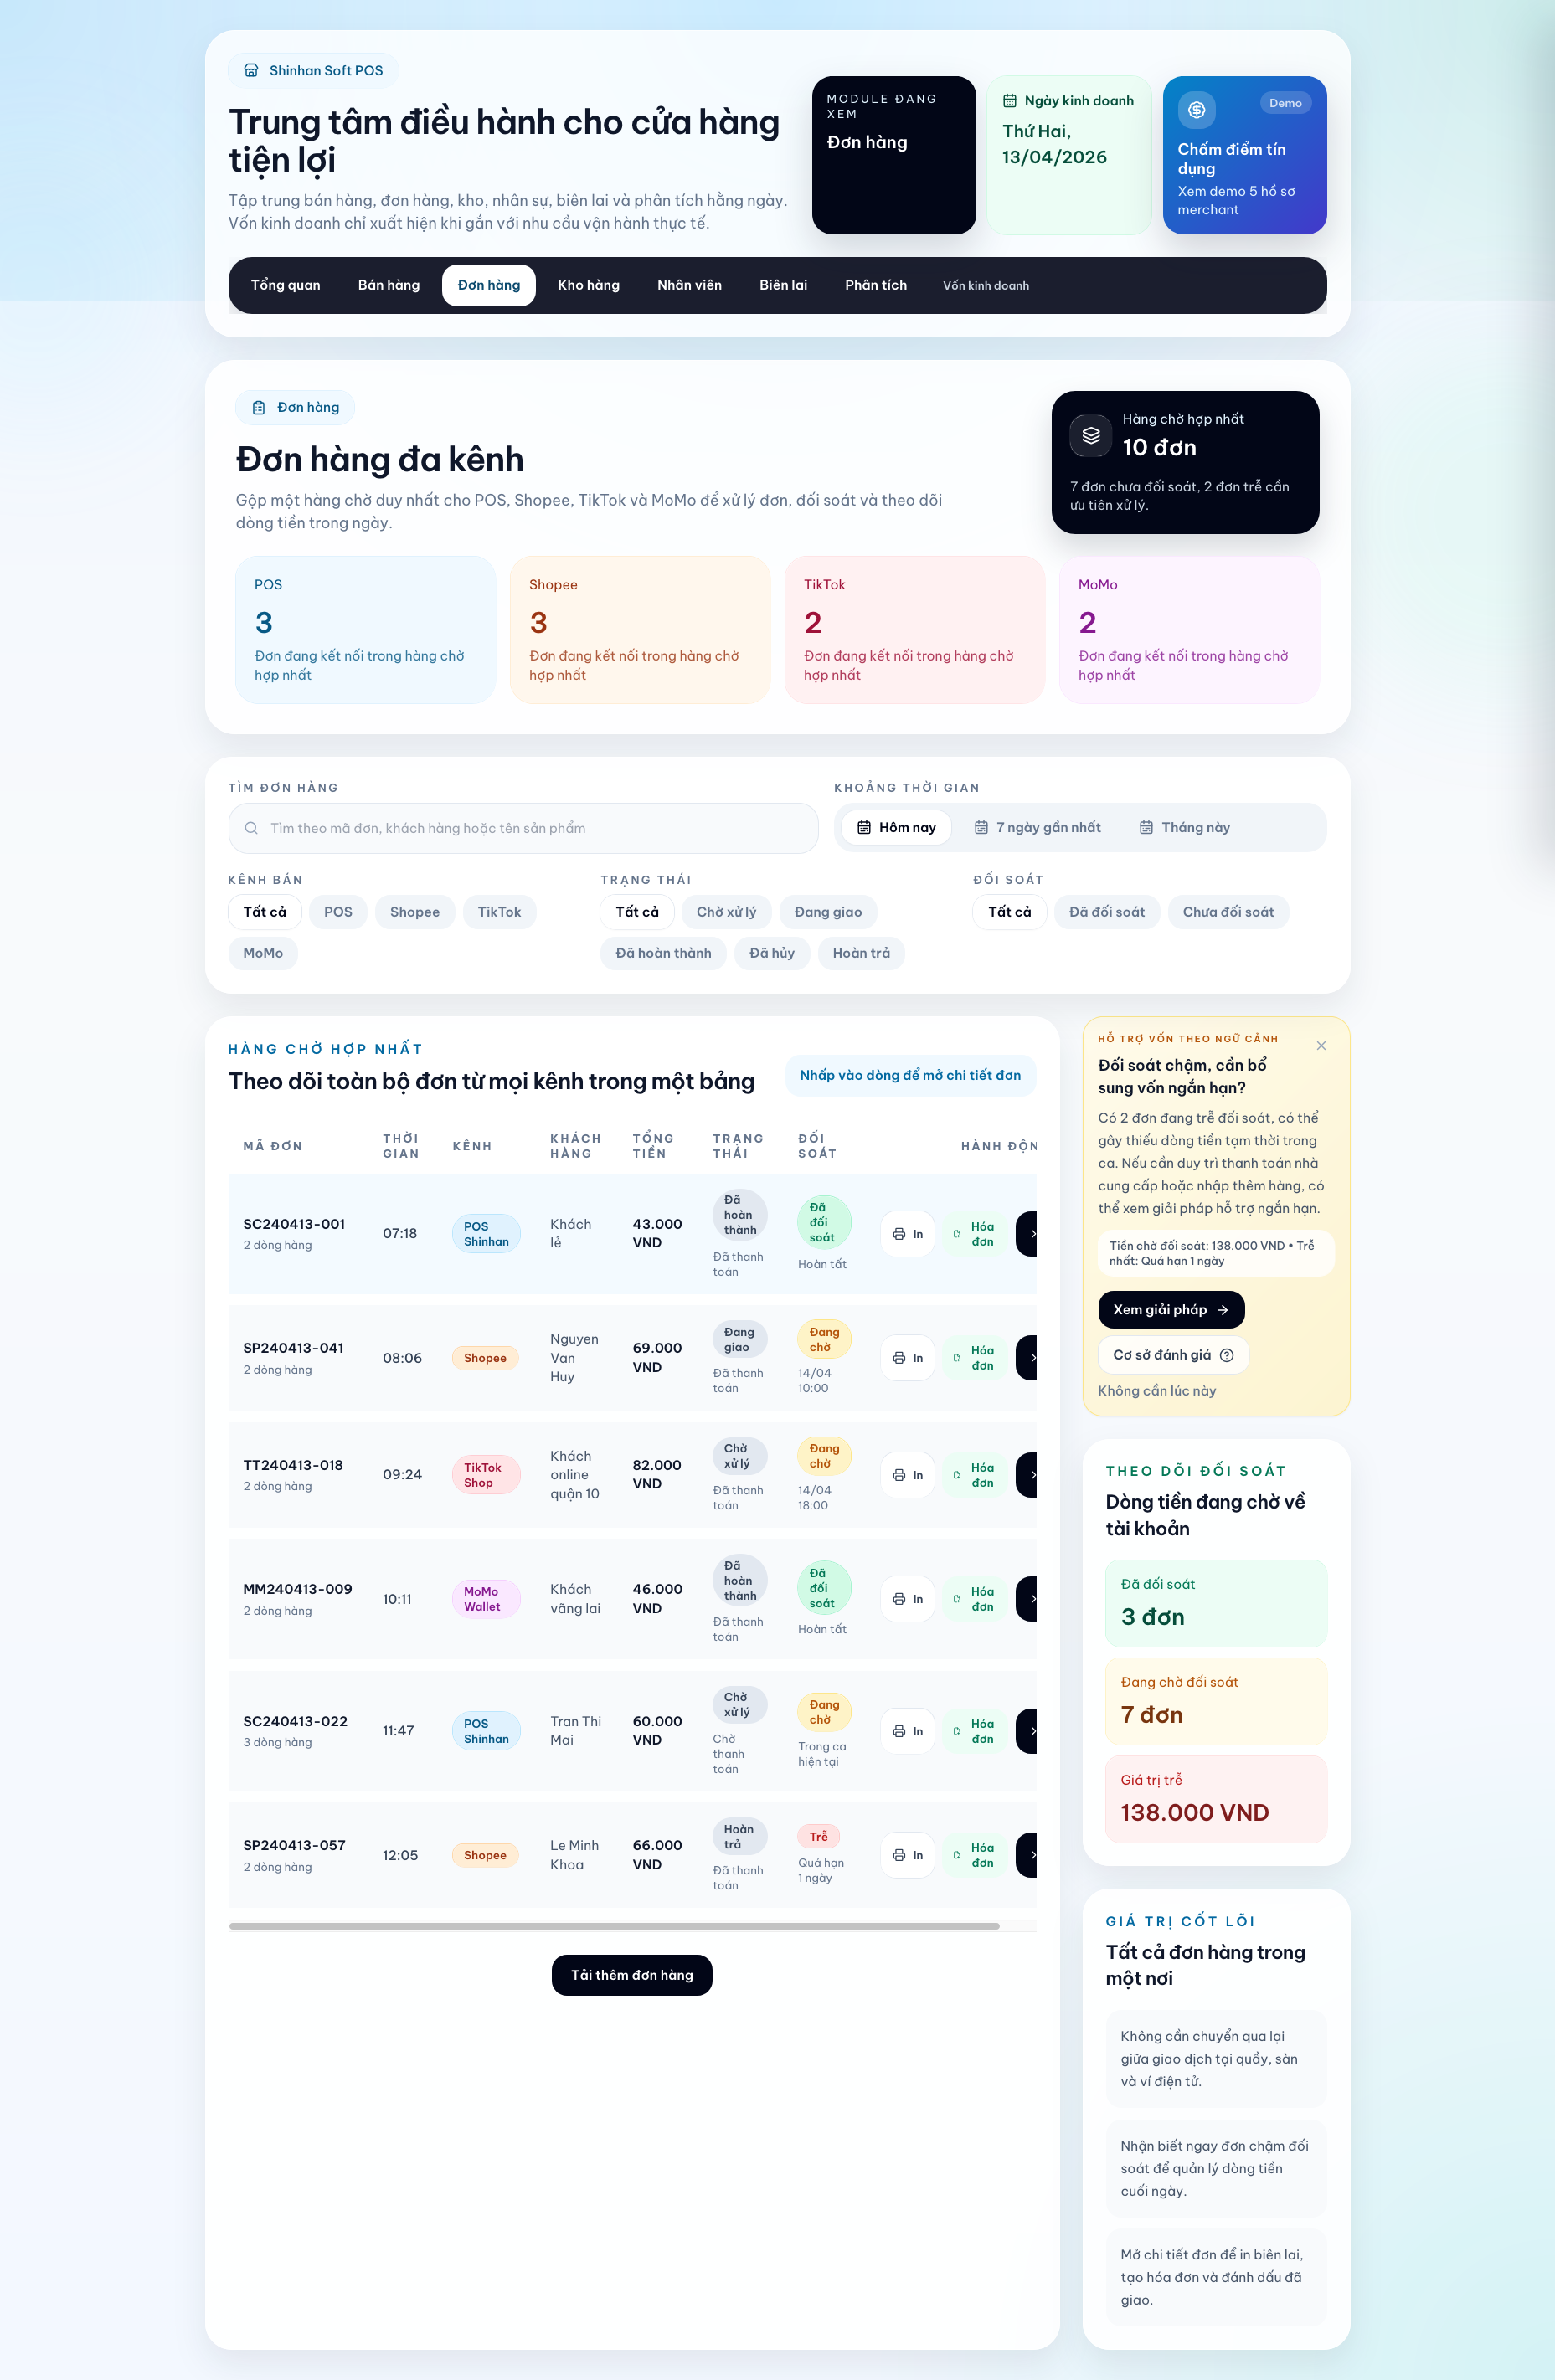
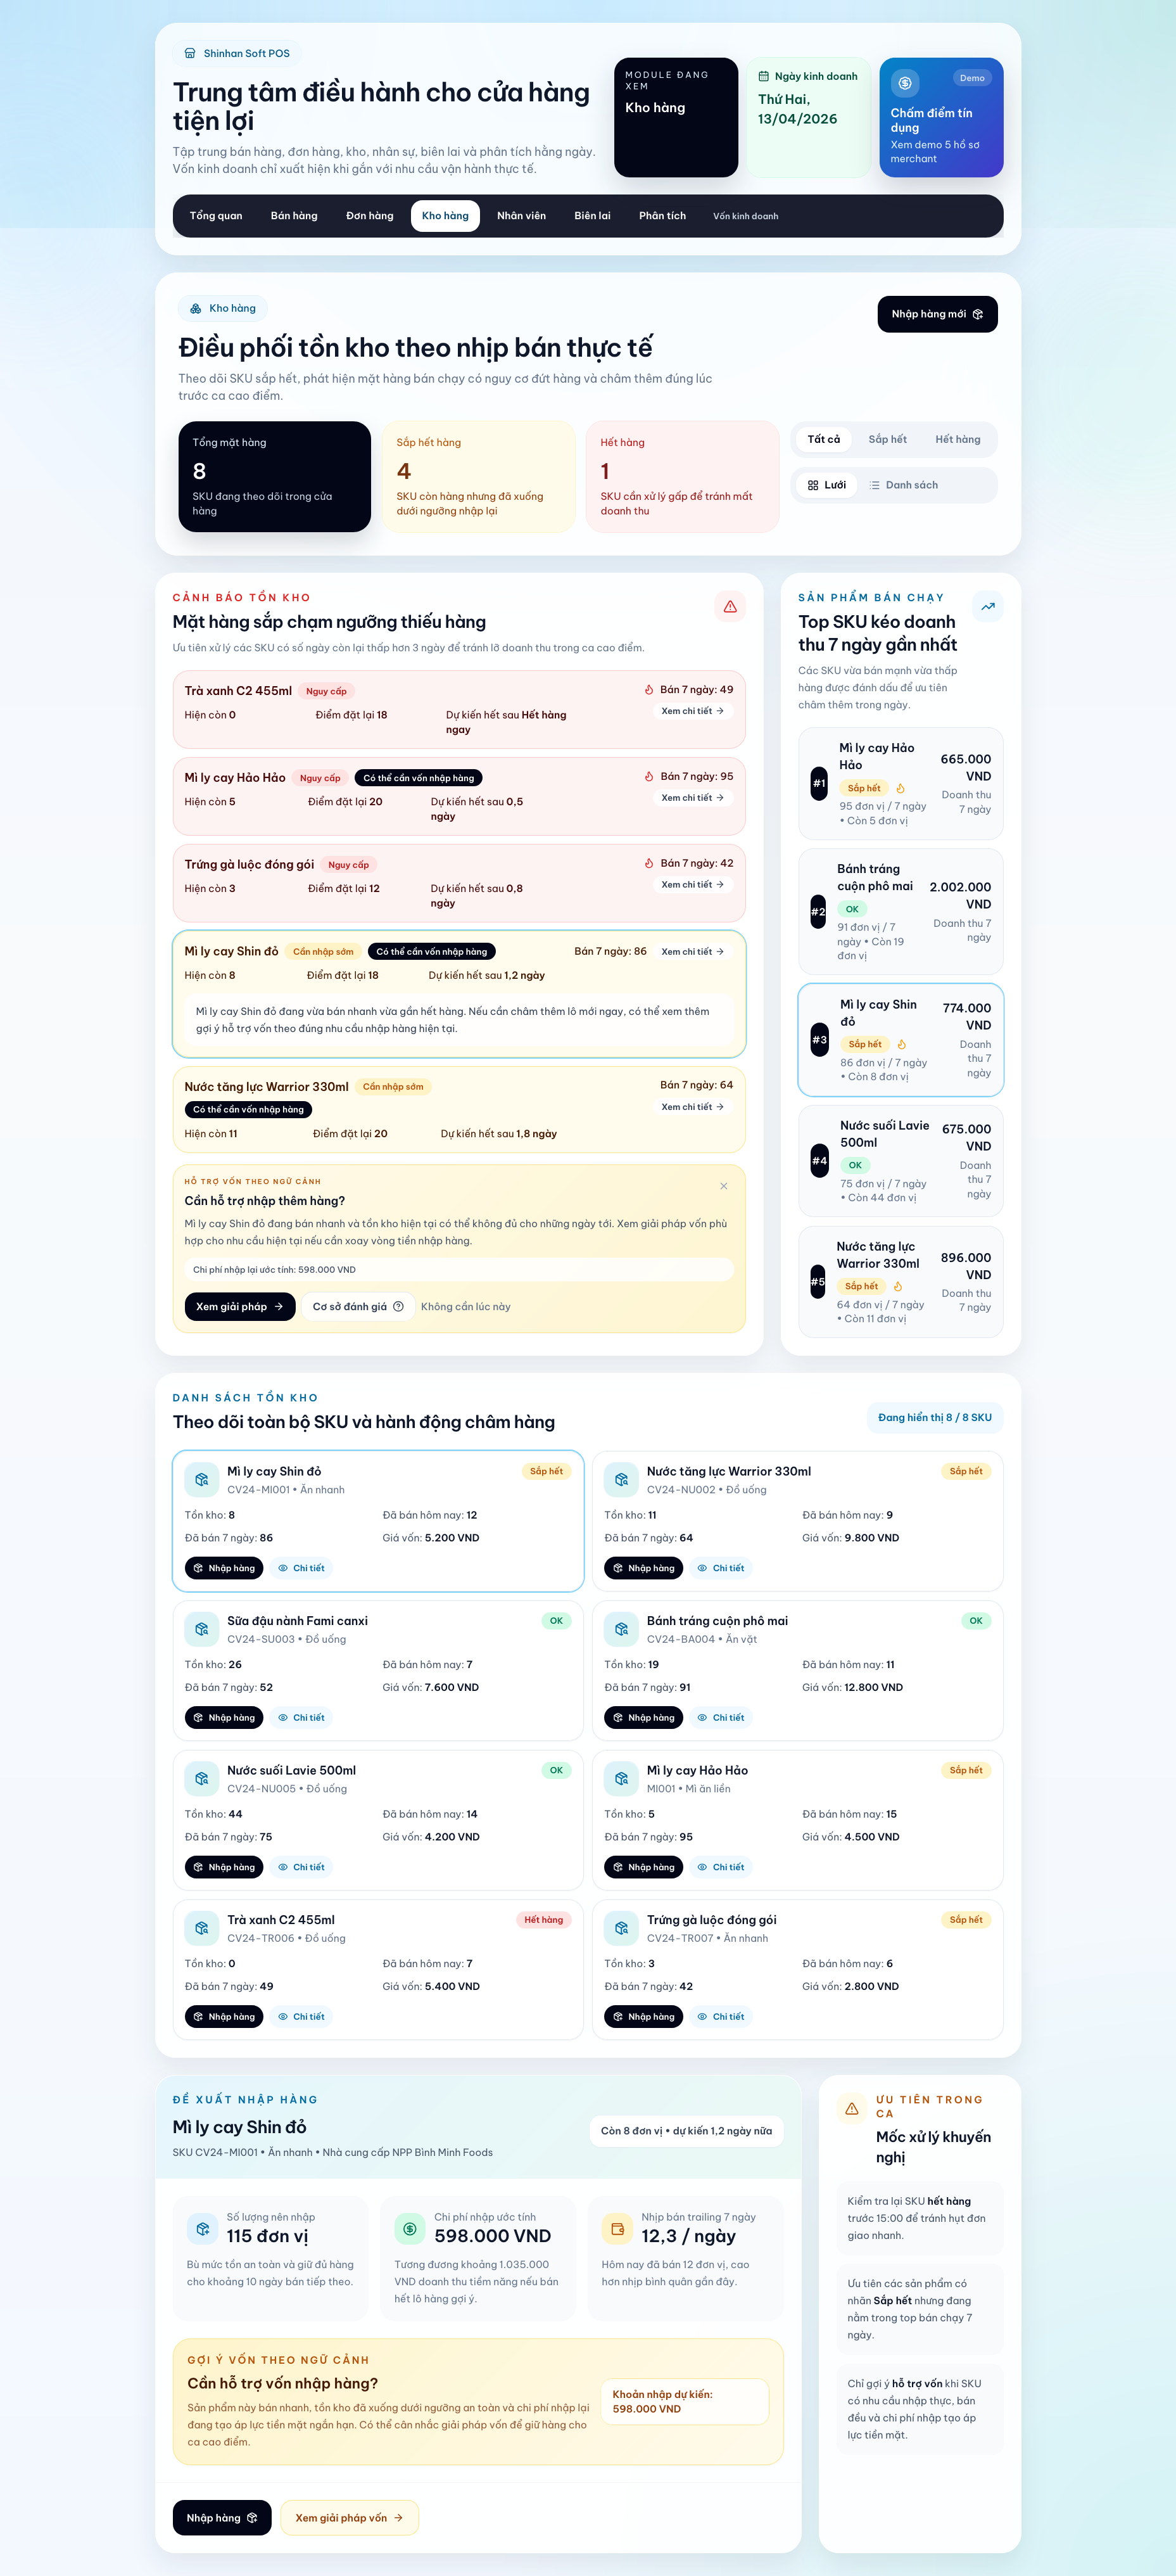
Shinhan Soft POS
The Merchant Operating System with Embedded Credit
Shinhan Future's Lab Hackathon
The Problem
Vietnamese SME Merchants Struggle Every Day
| Daily Pain Points | Current Reality |
|---|---|
| Managing POS, Shopee, TikTok, MoMo separately | 3 different apps for sales channels |
| Counting inventory manually every evening | Excel spreadsheets for inventory |
| Tracking staff hours and shift schedules | Paper timesheets for staff |
| Reconciling payments from 5+ platforms | 2+ hours nightly reconciliation |
| Cash flow gaps between sales and settlements | No visibility when cash will run out |
The Credit Gap
| What Banks Want | What SMEs Have |
|---|---|
| 6 months statements | Cash registers (POS) |
| Tax returns | Shopee/Lazada/TikTok sales |
| Collateral | MoMo wallet transactions |
| Formal business registration | Daily sales receipts |
40.5% of Vietnam's firms have bank loans - World Bank Enterprise Survey
The Solution
Shinhan Soft POS
The Alternative Credit Layer for Vietnam's SMEs
Alternative Credit Foundation
- POS + marketplace + e-wallet data fusion
- ML-based normalization turns fragmented activity into one merchant timeline
- Alternative credit profile built from explainable transaction patterns
- Signals banks can actually underwrite against
Embedded Capital Experience
- Embedded working capital at the point of need
- 72-hour approval target with policy-based pre-screening
- No traditional bureau file required
- Human-reviewed underwriting inside daily utility
Daily Utility
This is what merchants do EVERY DAY
| 🌅 Morning | ☀️ Midday | 🌆 Evening | 📈 Any Time |
|---|---|---|---|
| Check overnight orders; review inventory levels; assign staff shifts | Process in-store sales; fulfill marketplace orders; print customer receipts | Auto-reconcile all payments; see low-stock alerts; close shift reports | Check sales performance; manage staff; restock supplies |
Engagement Thesis
Why merchants come back every single day
❌ This is NOT a loan app
Merchants don't install loan apps. They install tools that run their business.
✅ This is their operating system
- Their business lives inside this app
- Trust is built through daily usage
- Transaction data accumulates naturally
- Financing appears only when they need it
Embedded Capital
Financing when it matters, not as an ad
Contextual Triggers
- 📦 Low stock alert -> Restock financing
- ⏳ Settlement delayed -> Cash flow advance
- 📈 Sales growing fast -> Growth capital
How it works
- Based on real business performance
- No separate application
- No credit check required
- Fast, transparent, fair terms
The Loan Product
Clean loan terms for eligible merchants
| Loan Range | $200 - $5,000 |
|---|---|
| Interest Rate | 15-18% APR |
| Term Length | 3, 6, or 12 months |
| Approval Time | 72 hours |
| Min. History | 90 days |
Demo Flow
How merchant activity turns into financing
- Step 1 - Install SOL POS -> Merchant starts using the operating tool every day.
- Step 2 - Data Normalization -> Transactions and consented mobile or telco signals are cleaned and standardized.
- Step 3 - Feature Profile Forms -> Audit-ready transaction features populate the scorecard profile.
- Step 4 - 90 Days of History -> Seasonality, stability, and risk features become reliable.
- Step 5 - Policy Eligibility -> Policy rules + score threshold determine eligibility for underwriter review.
- Step 6 - Loan Offer Shown -> Illustrative amount and terms appear inside the workflow.
- Step 7 - Funds in 72 Hours -> Approved merchants receive funds after underwriting and policy checks.
AI Governance Framework
Explainable scoring with human review by default
Human-in-the-Loop as Default
- Every score/recommendation -> human review
- Fixed reason codes accompany each output
- LLM translates only approved reason codes
- Inputs, weights, bins logged for audit
What AI Actually Does (scoring path)
- Transaction cleaning and categorization
- Merchant behavior feature engineering
- WoE logistic scorecard -> primary model
- EBM challenger -> validation only
What AI Does Not Do
- Final credit decisions (bankers decide)
- Custom explanations (approved codes only)
- Black-box inference in scoring path
Explainable Credit Intelligence Layer
Where Shinhan's underwriting logic stays transparent
| Capability | What it does |
|---|---|
| ML-Based Data Normalization | POS, marketplace, e-wallet, and telco metadata are fused into one audit-ready merchant timeline. |
| WoE Scorecard Core | Fixed bins, weights, and reason codes power the primary scorecard. An EBM challenger runs in parallel for accuracy checks. |
| Statistical Pattern Features | Tet, monsoon, and household-business effects become peer-normalized features inside the scorecard. |
| AI-Assisted Underwriting | Policy rules and score thresholds create a recommendation pack. Human review stays standard, and the LLM only translates approved codes. |
Every score is reproducible from logged inputs, weights, bin boundaries, and reason codes.
The Data Flywheel
The Data Flywheel
More merchants -> More data fused -> Better scorecards -> Faster underwriting -> Better risk features -> Lower defaults -> Better portfolio -> Lower cost of capital -> Lower rates -> More demand
Performance data improves the next validation cycle.
Competitive Advantage
| Traditional POS | Marketplace Apps | Bank Loans | Shinhan Soft POS | |
|---|---|---|---|---|
| Multi-channel orders | ❌ | ✅ Only own channel | ❌ | ✅ All channels unified |
| Inventory management | ⚠️ Basic | ❌ | ❌ | ✅ Smart alerts |
| Staff management | ❌ | ❌ | ❌ | ✅ |
| Automatic reconciliation | ❌ | ❌ | ❌ | ✅ |
| Contextual financing | ❌ | ❌ | ❌ | ✅ Embedded |
| Daily usage frequency | Daily | Weekly | Monthly | Multiple times per day |
Sources: MISA Lending (misa.vn), Shopee SEasy (TPBank partnership), Validus Vietnam, Techcombank ShopCash
Why This Matters
- Existing solutions use one data channel only
- Our approach combines POS + Marketplace + E-wallet data - not yet disclosed as a combined approach in Vietnam
Payment Safety
How we protect merchants and Shinhan
3 statistical safety patterns we monitor:
| 🔄 Circular Wallet Flows | 🛒 Synthetic Orders | ⚡ Velocity Anomalies |
|---|---|---|
| Rule-based flow checks flag repeated wallet loops that appear to inflate transaction volume. | Cross-checks compare payment, address, and fulfillment trails to surface synthetic orders. | Threshold and peer-baseline checks surface unusual spikes at odd hours or from new devices. |
Vietnam-Specific Risk Signals
Peer-normalized statistical signals tuned to how local merchants actually operate:
| 🎊 Tet Season Patterns | 🌧️ Monsoon Disruption | 👨👩👧 Family Business Structures |
|---|---|---|
| Lunar-calendar seasonality factors help prevent holiday spikes from being mistaken for permanent growth. | Regional baseline adjustments separate weather-driven demand drops from true merchant deterioration. | Linked-counterparty features capture shared household cashflow patterns while keeping the score fully auditable. |
Compliance Roadmap
Path to Production
| Phase 1 | Phase 2 | Phase 3 |
|---|---|---|
| Sandbox (Month 1-2): Anonymized data only; internal testing; score + reason codes prepared for analyst review; SBV regulatory consultation | Pilot (Month 3-4): Live data with full consent; POS operations first; automated score calculation and policy checks; human review remains standard; compliance audit trail | Production (Month 5-6): Full POS rollout; contextual capital offers; explainable scorecard + audit trail; human-reviewed origination at 100+ merchants |
The Ask
What we need
- Access to merchant/payment infrastructure
- Partnership with existing POS providers
- Pilot merchant cohort for validation
- 6 months to prove daily engagement
What you get
- The daily merchant operating system for Vietnam
- High frequency merchant relationship
- Embedded financing monetization layer
- Data asset that compounds with every transaction
What This Is
We haven't launched a production credit product yet.
We don't have live API integrations yet.
We don't have a backtested model yet.
What we HAVE built:
- Working early system showing normalized data -> explainable score concept
- ML-based data fusion and scorecard pipeline architecture
- Clear path to 6-month early product launch
This is an early product proposal with a defined roadmap.
The Close
Every sale is captured.
Every inventory alert is acted on.
Every merchant grows with Shinhan.
Position Shinhan as the bank merchants use every day.
Appendix: Research Sources
Market Context
| Source | What It Verifies |
|---|---|
| Vietnam News - Digital Loans Open New Doors for SMEs | SMEs struggle to access bank credit; digital lending growing |
| Techcombank - MISA Lending | Existing bank alternative-data lending product |
| MISA Lending - MB Partnership | Digital SME lending via accounting software |
Existing Competitor Products
| Source | What It Verifies |
|---|---|
| Shopee Seller Education - SEasy | Shopee seller financing product exists |
| Validus Vietnam | Active SME lender in Vietnam |
| Techcombank MerchantOne | Bank merchant acceptance product |
| Techcombank SoftPOS | Bank SoftPOS product |
| Techcombank ShopCash | Bank merchant lending product |
Appendix: Model Explainability
WoE Scorecard & EBM Challenger
WoE Logistic Scorecard
Converts transaction history into a single score (300-850 scale) with fixed reason codes. Every input, weight, and bin boundary is logged and reproducible. Regulators prefer it because every decision is fully auditable.
EBM Challenger Model
A glass-box ML model that runs alongside the scorecard for accuracy validation. Each feature's contribution to the final score is visible. Used for validation only - not final decisions.
Why Not Deep Learning or LLM for Scoring?
Black-box models are prohibited by most banking regulators - no one can explain why a merchant was declined. Our LLM is limited to translating pre-approved reason codes into natural language. It never makes or modifies credit decisions.
Every score is reproducible from logged inputs, weights, bin boundaries, and reason codes.
Built With
- adenosin-triphosphaste
- alibaba-model-studio
- bmad
- claude-sonnet-4.6
- cloudflare-workers
- coffee
- dola-seed-2.0-pro
- gpt-5.4
- grok-code-fast-1
- groq
- groq-compound-mini
- kilo
- magic
- minimax-m2.5-highspeed
- minimax-m2.7-highspeed
- neovim
- openrouter
- puter-js
- qwen-3.6-plus
- qwen3-coder
- qwen3-coder-480b-a35b-instruct
- react-router
- tailscale
- termux
- vibe-engineering
- waifu
- zellij

Log in or sign up for Devpost to join the conversation.