-
-
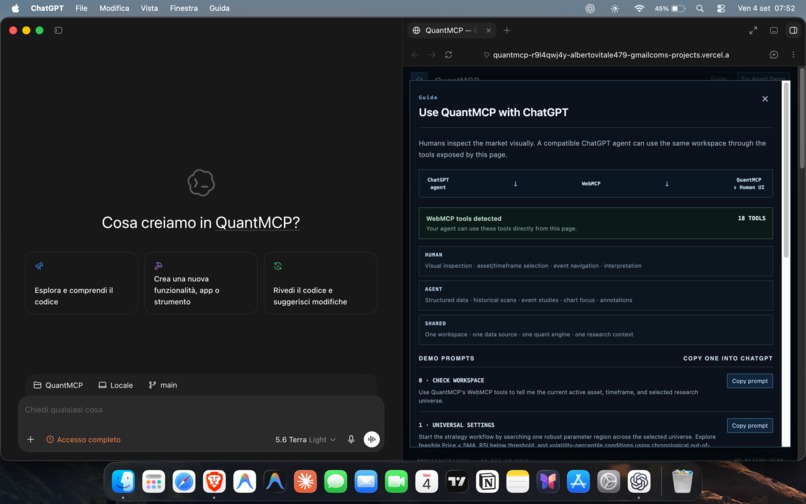
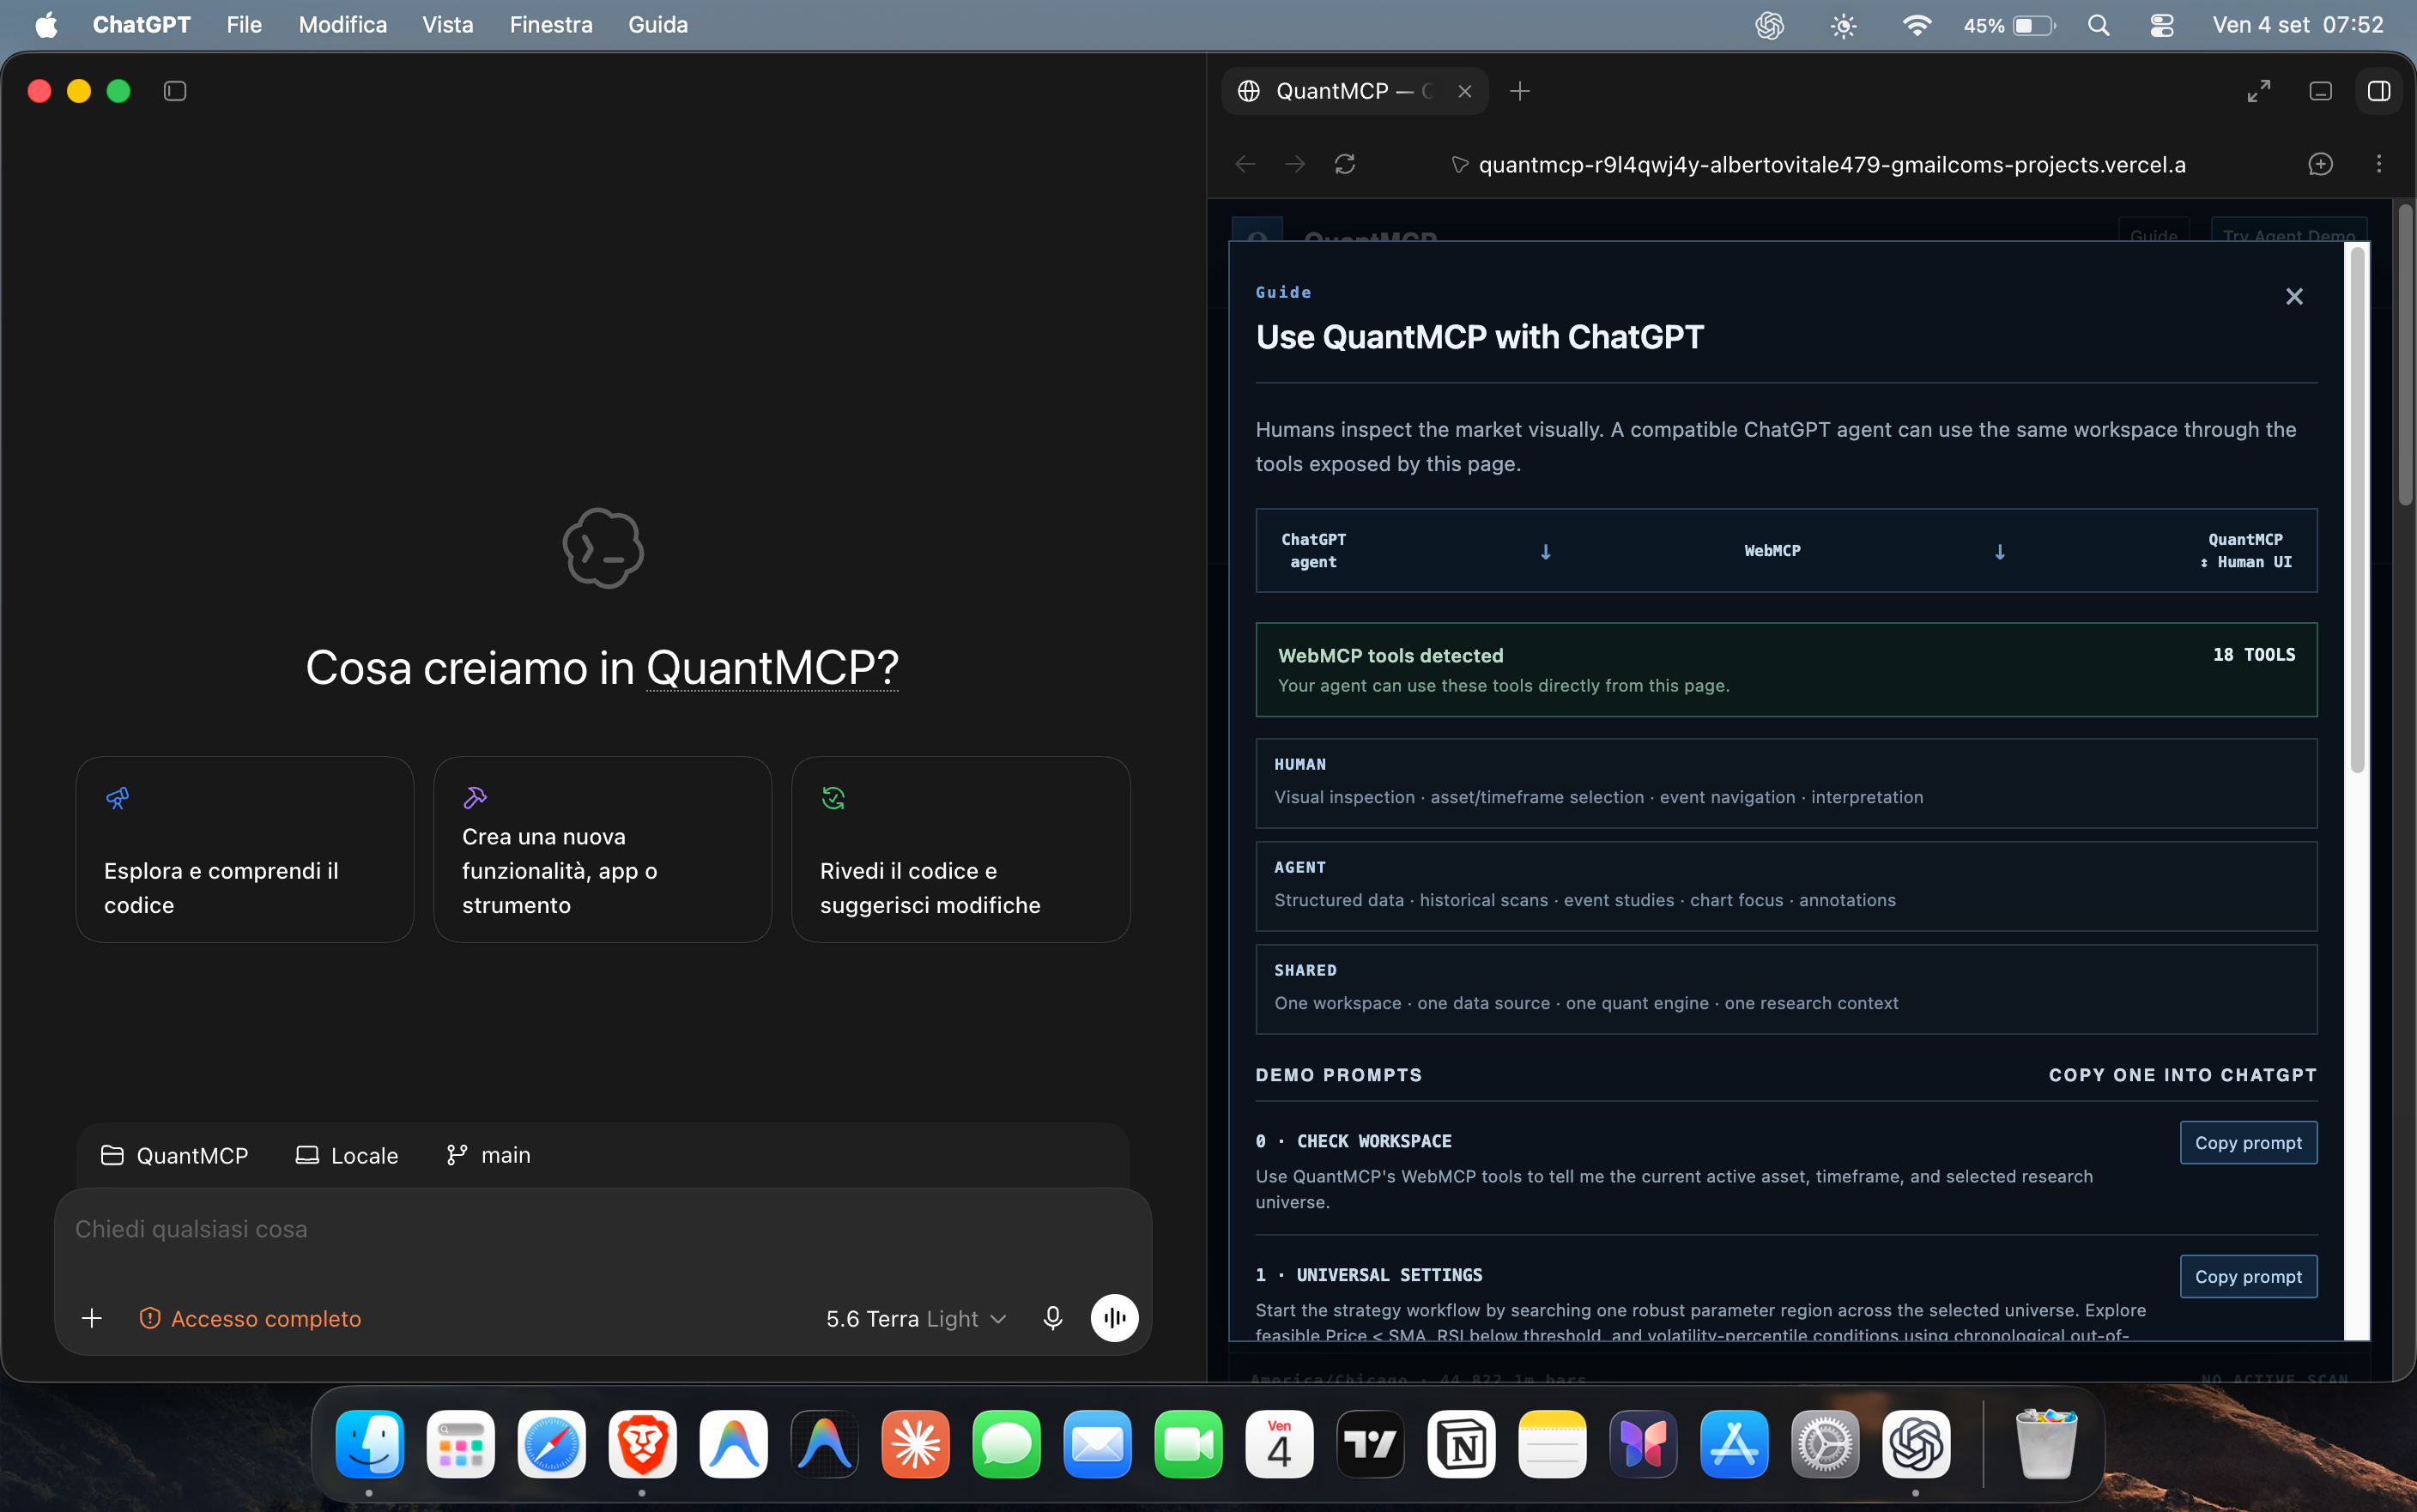
tells us explicitly when it is connected correctly
QuantMCP — a shared research workspace for human + AI market analysis
QuantMCP was built for a simple problem: quantitative research often becomes a disconnected chain of charts, prompts, parameters, and spreadsheets. That makes it hard to reproduce a strategy, compare alternatives, or review the quality of someone’s work.
QuantMCP turns that chain into one visible, shared workflow. A human researcher and an MCP-enabled agent work on the same active asset, timeframe, historical events, saved strategy definition, event study, trade simulation, chart focus, and research notes.
What it does
The workflow is intentionally ordered for transparent competition review:
- Select a research universe.
- Search feasible shared parameters with chronological out-of-sample validation.
- Validate the saved universal region across assets and rank them.
- Optionally refine the best-ranked asset.
- Run an event study using the saved strategy definition.
- Run a deterministic historical trade simulation with explicit entry, stop, target, holding-period, and OHLC collision rules.
- Review the strongest and weakest historical cases together.
This means Event Study and Trade Simulation do not silently use unrelated conditions: they inherit the saved robust strategy configuration.
WebMCP integration
QuantMCP exposes 18 browser-native WebMCP tools. The agent can inspect the active workspace, query structured historical conditions, calculate indicators and forward returns, compare timeframes, run universe and parameter research, simulate trades, focus chart ranges and trades, and save research findings.
The human sees the same evidence immediately in the UI. The agent does not place orders and the app is designed for historical research only.
Reliability and performance
The project uses real continuous-futures demo datasets across eight assets. Heavy condition scans, parameter searches, timeframe comparisons, event studies, and trade simulations run in background workers, keeping the chart responsive and showing real progress instead of appearing frozen.
To make the experience practical on desktop and mobile, QuantMCP includes a fast Intraday Core preset, keeps all assets available for full validation, bounds expensive universal searches, caches datasets by asset and timeframe, and progressively renders large trade lists.
What I learned
The hardest part was not building individual quant calculations; it was preserving one reliable shared state across human controls and agent tool calls. I learned that a useful AI research interface needs explicit dependencies, reproducible definitions, transparent out-of-sample evidence, and a UI that makes the next correct step obvious.
Built With
- charts
- data
- finance
- financial
- github
- lightweight
- quantitative
- react
- responsive
- typescript
- vercel
- vite
- vitest
- web
- webmcp
- workers

Log in or sign up for Devpost to join the conversation.