-
-
-
-
-
-
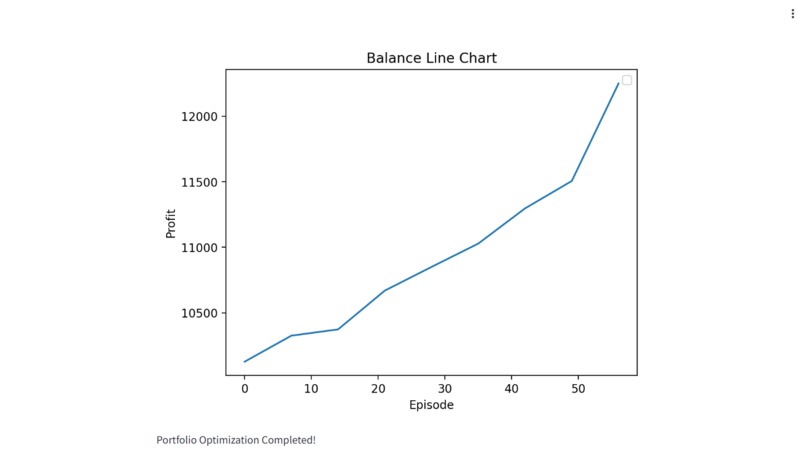
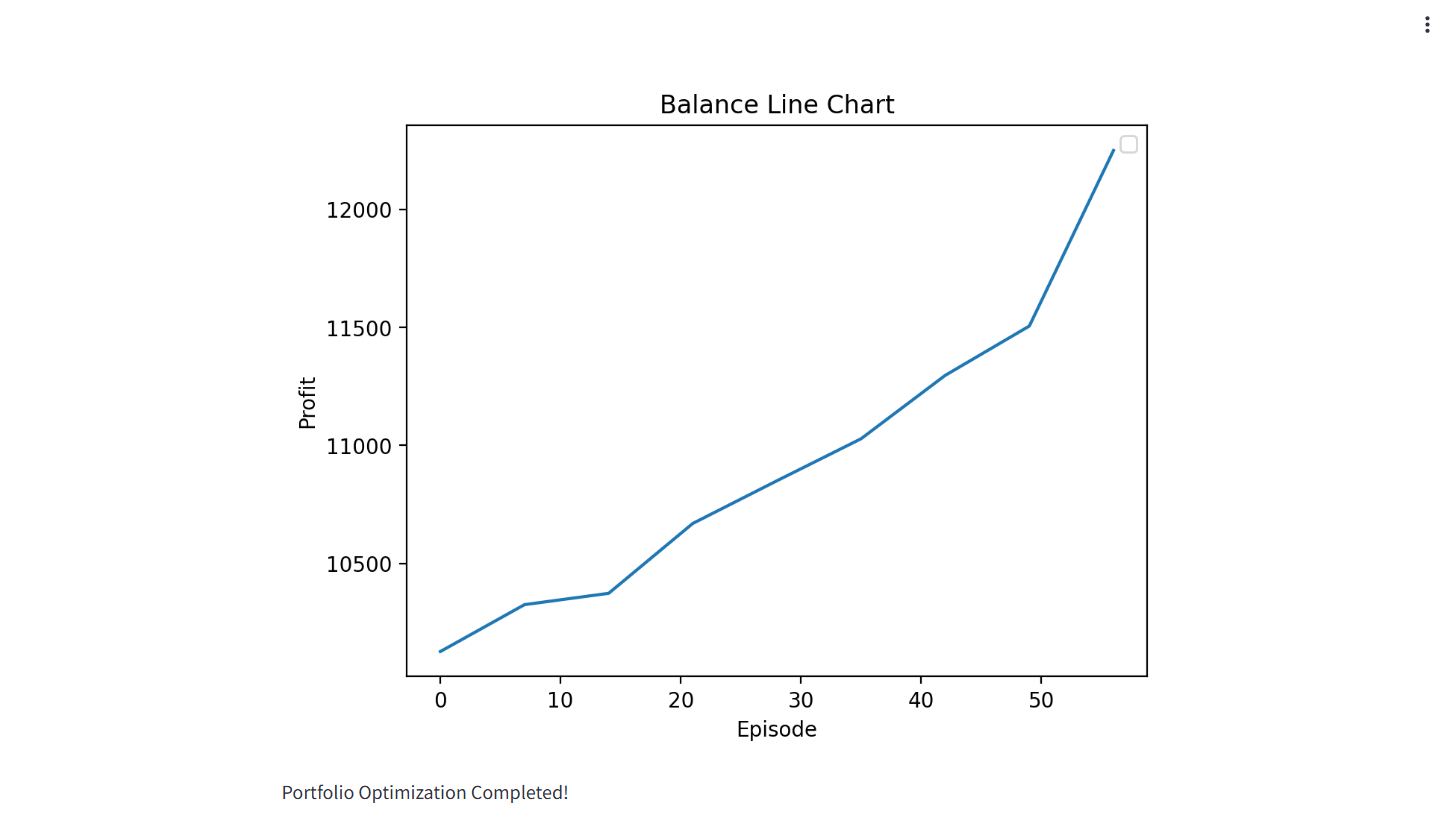
Line chart of balance vs time
-
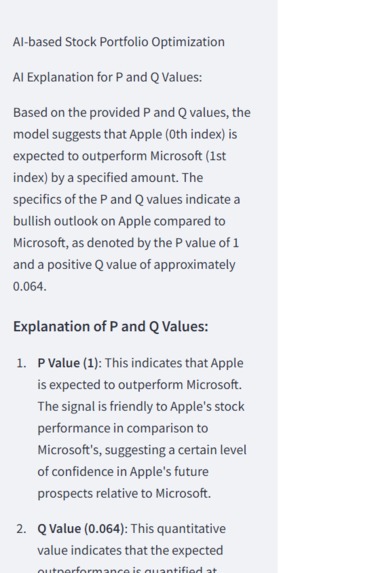
LLM generated summary of price changes.
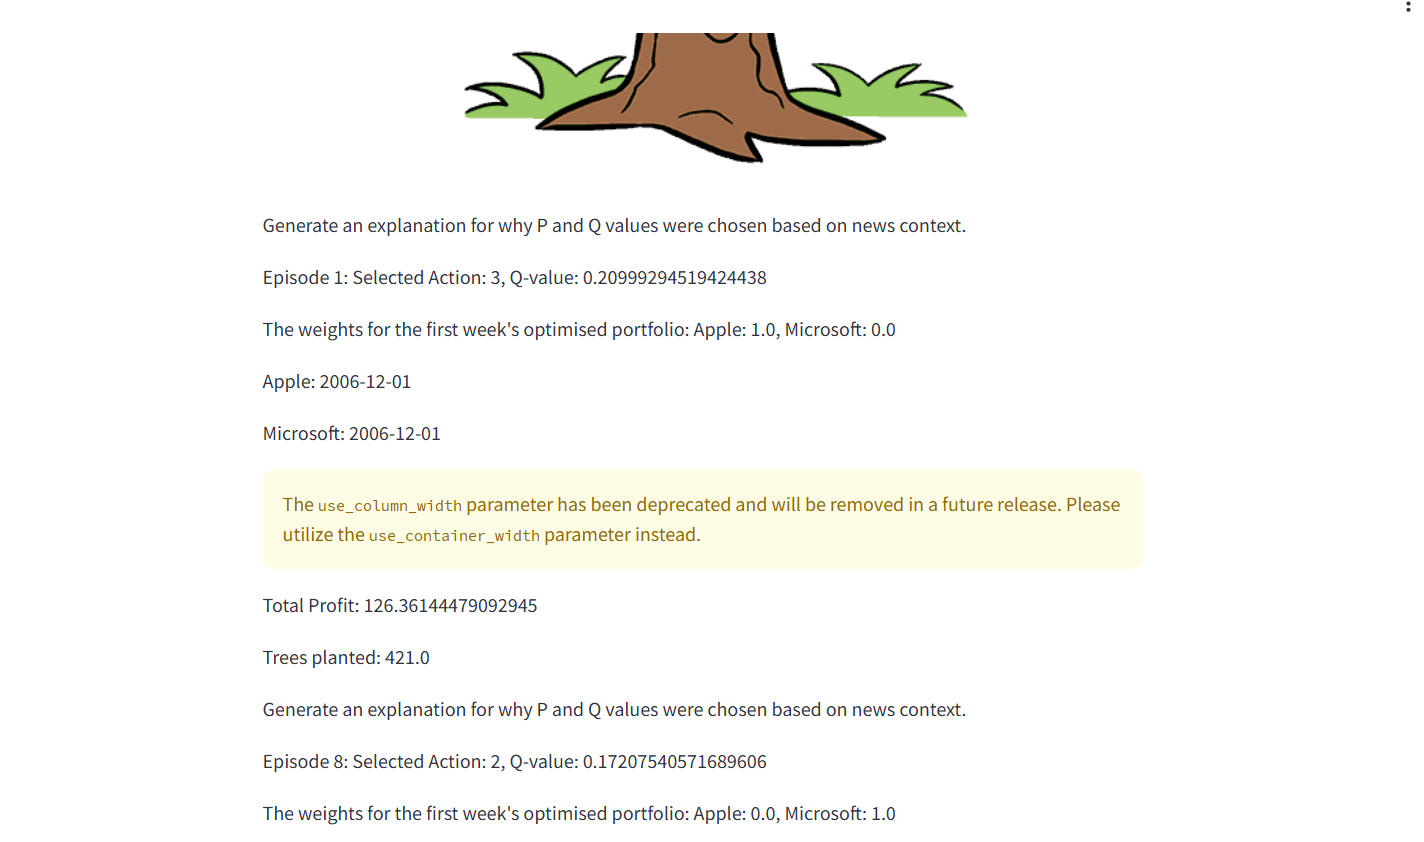
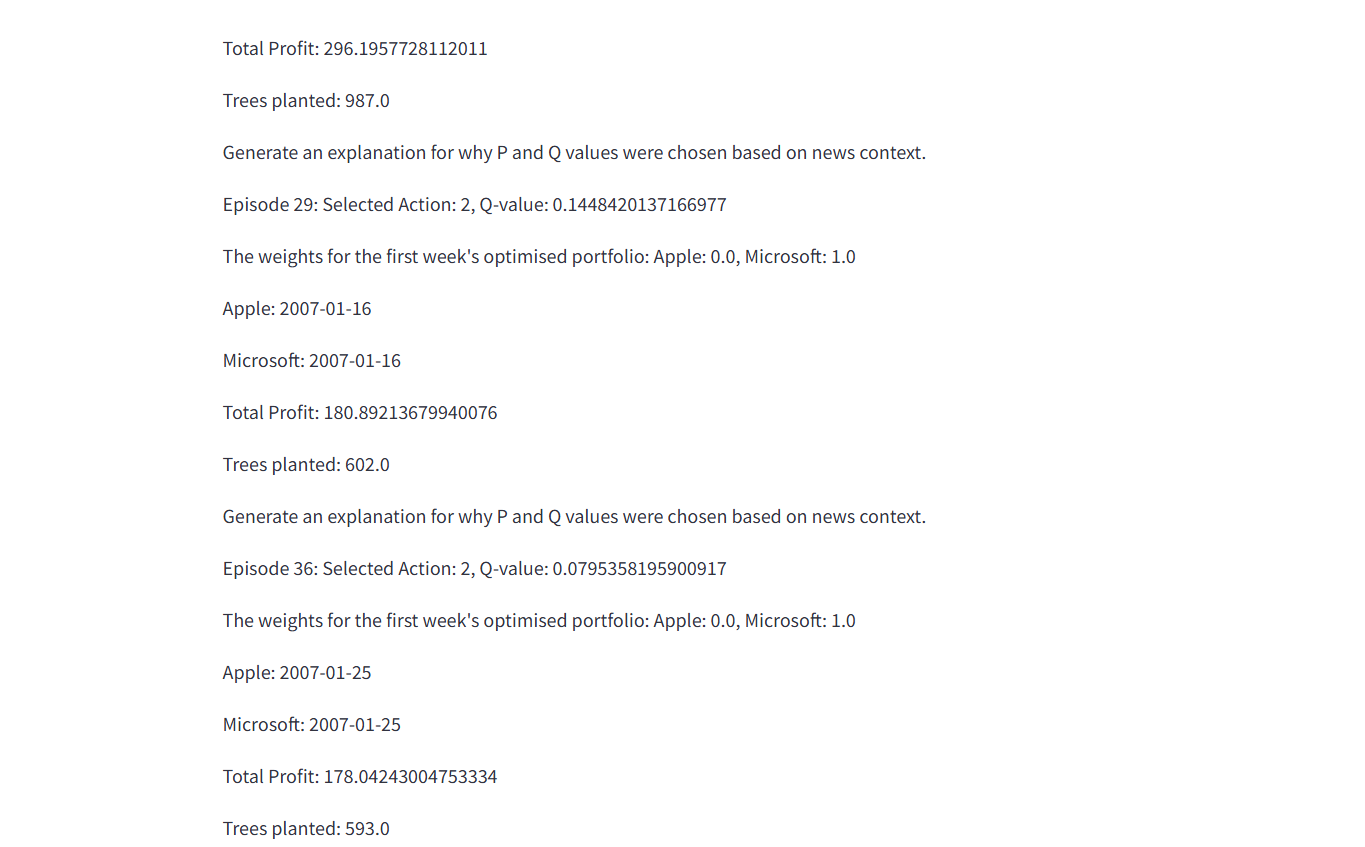
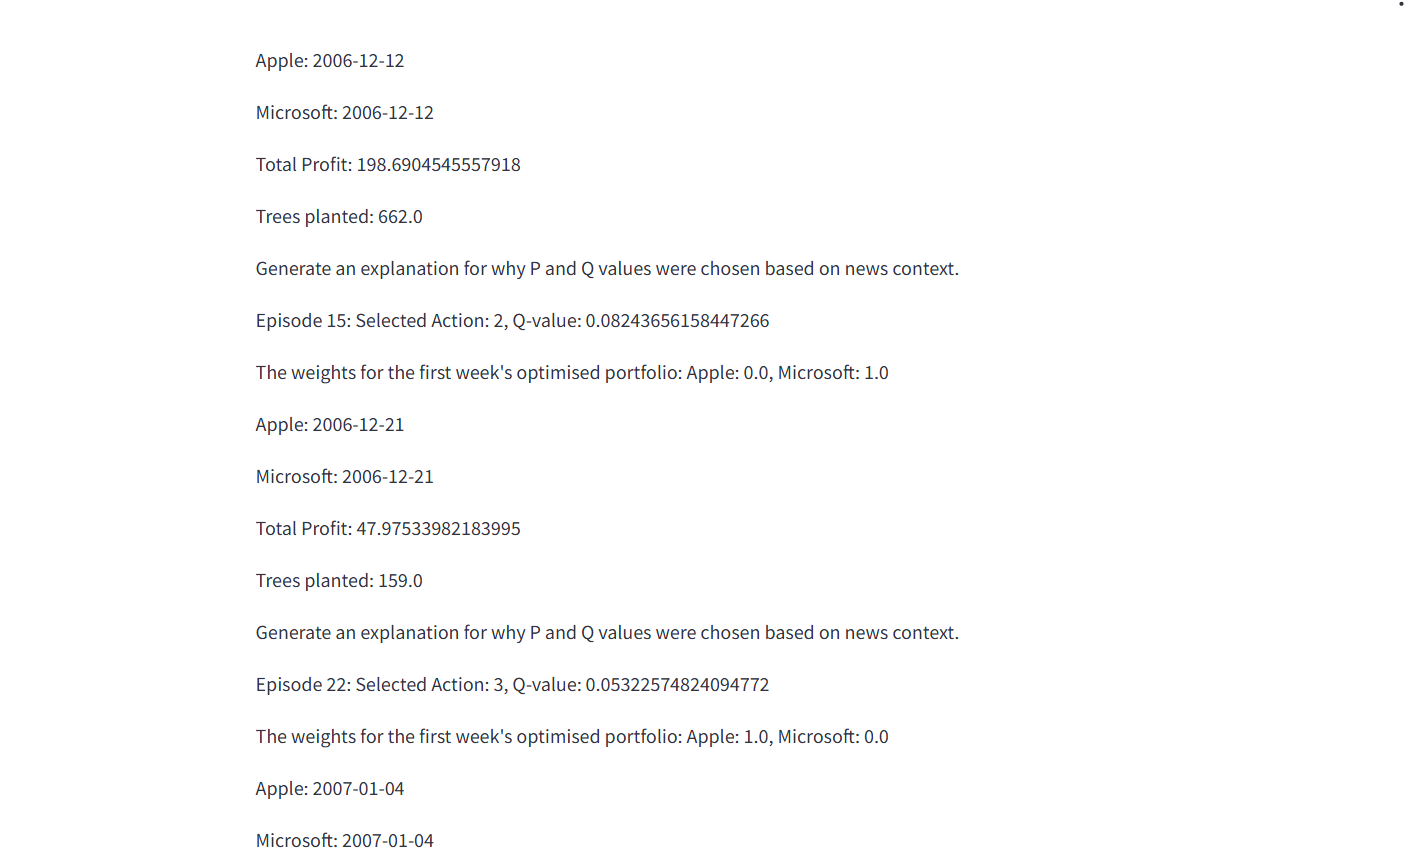
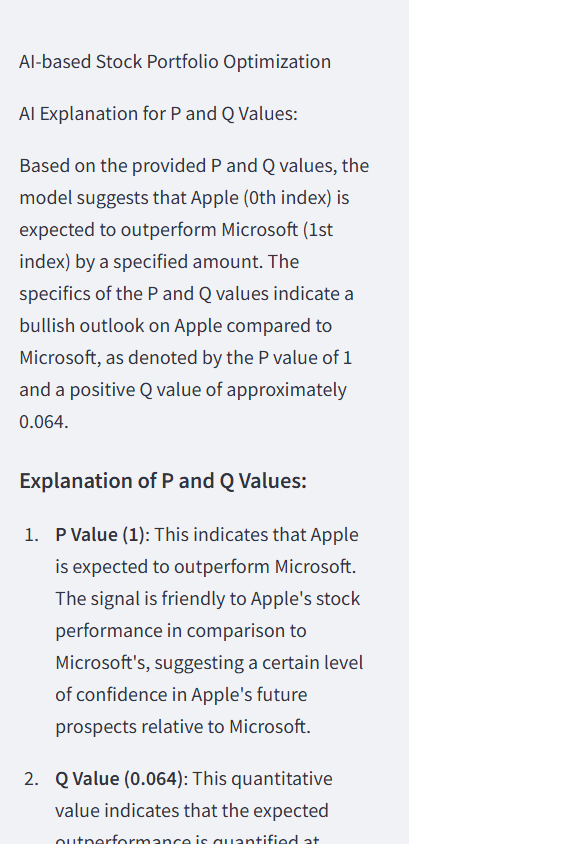
Our project enhances traditional portfolio optimization by integrating AI with Modern Portfolio Theory (MPT) and the Black-Litterman Model. While MPT maximizes returns with minimal risk, Black-Litterman incorporates investor views for more stable allocations. We took it a step further by using BERT to analyze vast amounts of financial news in real time, enabling data-driven market insights to refine portfolio decisions. This hybrid approach combines financial expertise with AI-driven adaptability, ensuring optimal returns while managing risk effectively.
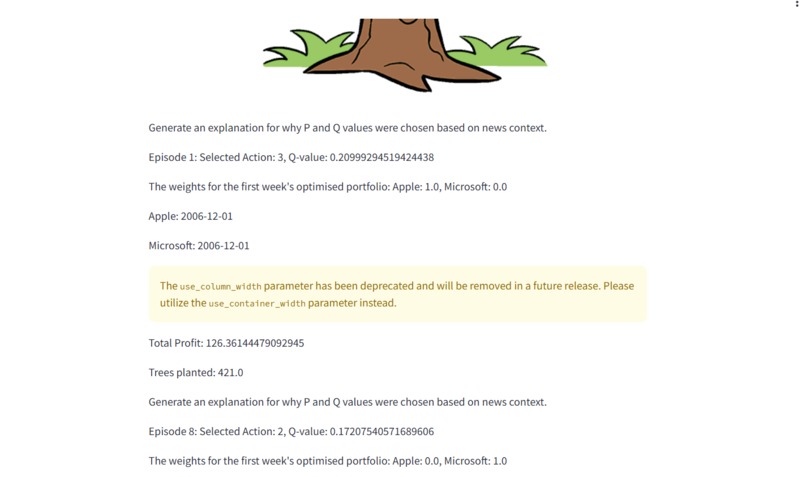
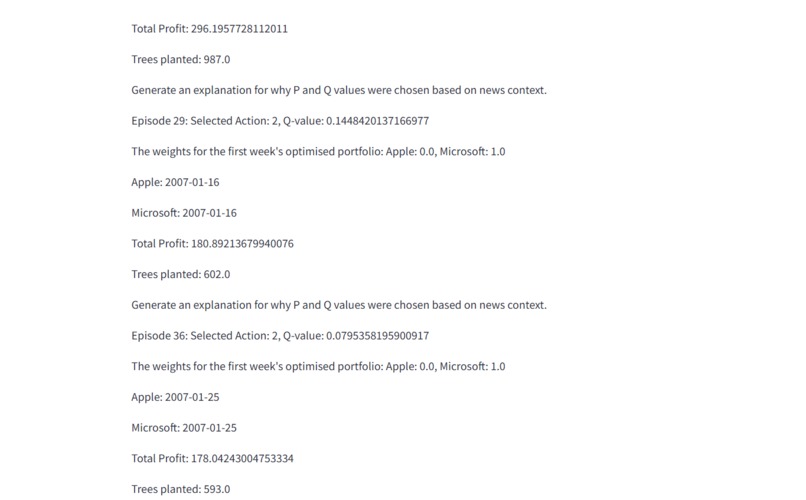
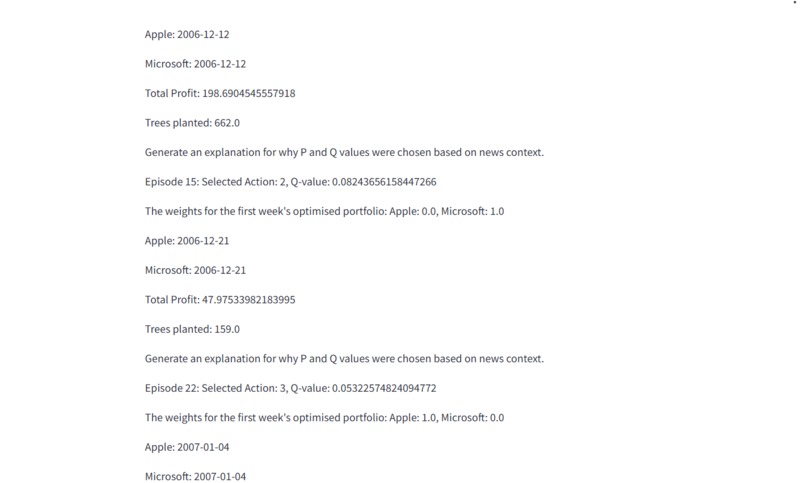
We built a web application that applies this model, utilizing reinforcement learning to optimize asset allocation dynamically. By simulating investments with paper money, our system demonstrated positive returns, validating its effectiveness. Challenges like large-scale data processing, model integration, and risk management required innovative solutions, but our results show the potential of AI-driven portfolio optimization in modern finance.


Log in or sign up for Devpost to join the conversation.